Does Car Insurance Affect Your Personal Credit Score
Yes, car insurance can affect your credit score in specific ways, but the impact depends on the type of credit check and your financial habits. When insurers pull your credit for underwriting, a hard inquiry may temporarily lower your score, while soft inquiries have no effect. Understanding how credit-based insurance scores work helps you make smarter decisions about coverage and protect your financial health.
Have you ever wondered whether buying a new car insurance policy could hurt your credit? It is a question many drivers ask, especially when they see their insurer asking for permission to check their credit. The short answer is yes, car insurance can affect your credit score, but the full story is more nuanced than you might think. Let us break it all down so you understand exactly what is happening behind the scenes.
When you apply for car insurance, the company often runs a credit check. This check can be either a hard inquiry or a soft inquiry. Each type affects your credit differently. A hard inquiry may lower your score slightly, while a soft inquiry has no impact at all. Understanding this difference is key to managing your financial health and keeping your credit score in good shape.
In this article, we will explore exactly how car insurance interacts with your credit. We will cover what insurers look at, how credit-based insurance scores work, and what you can do to minimize any negative effects. By the end, you will feel confident and informed about your insurance decisions.
Key Takeaways
- Hard credit checks from insurance companies can temporarily dip your credit score by a few points.
- Soft credit checks have zero impact on your credit score and are used for rate shopping.
- Credit-based insurance scores are different from traditional credit scores and focus on payment patterns.
- Payment history and credit utilization are the biggest factors that insurers look at.
- Some states have banned or restricted the use of credit in car insurance pricing.
- Shopping around for insurance quotes does not hurt your credit if done within a short time window.
- Improving your credit can lead to lower insurance premiums over time.
📑 Table of Contents
- How Car Insurance Companies Use Your Credit
- Hard Inquiries vs. Soft Inquiries: What Is the Difference?
- Does Shopping for Car Insurance Hurt Your Credit?
- Which States Restrict or Ban Credit-Based Insurance Scoring?
- How Your Credit Score Affects Your Insurance Premium
- Can You Improve Your Credit to Lower Insurance Costs?
- Common Mistakes People Make With Insurance and Credit
- Final Thoughts
How Car Insurance Companies Use Your Credit
Most people do not realize that car insurance companies check credit as part of the application process. It is not about judging your character. Instead, insurers use credit information to help predict risk. Studies show that people with higher credit scores tend to file fewer claims. This makes credit a useful tool for risk assessment in the insurance industry.
What Is a Credit-Based Insurance Score?
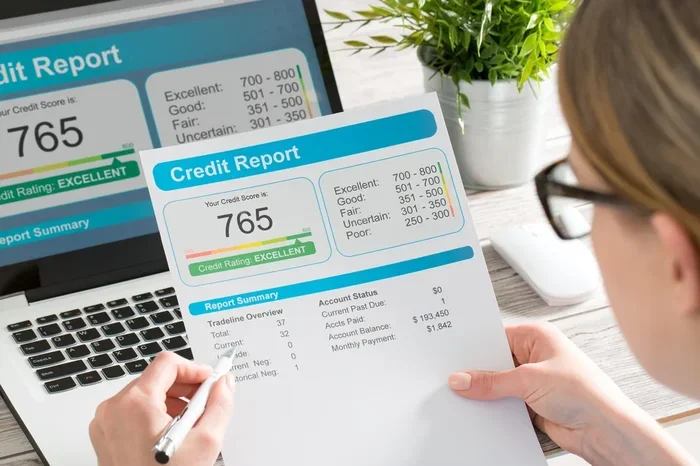
A credit-based insurance score is a special number that insurers use to evaluate your financial responsibility. It is not the same as your regular FICO score or VantageScore. While traditional credit scores focus on your ability to repay loans, insurance scores focus on how well you manage your finances over time. Factors like payment history, length of credit history, and credit utilization all play a role.
Here are the key factors that go into a credit-based insurance score:
- Payment history — Do you pay your bills on time?
- Credit utilization — How much of your available credit are you using?
- Length of credit history — How long have you had your accounts open?
- Types of credit — Do you have a mix of credit cards, loans, and other accounts?
- Recent credit inquiries — Have you opened several new accounts recently?
Insurers do not look at your income, job, or savings when calculating this score. They only focus on your credit behavior. This is why maintaining good financial habits matters even if you do not think you have a loan or mortgage.
Why Do Insurers Check Credit?
Insurance companies use credit checks because they have found a strong correlation between credit behavior and claim likelihood. If you manage your finances responsibly, you are statistically less likely to file a claim. This does not mean people with lower credit are bad drivers. It simply means insurers use data to set their insurance premiums. The goal is to price policies fairly based on risk models.
Also, when you compare quotes from multiple insurers, each company may run its own credit check. This is why shopping around for car insurance can sometimes lead to multiple inquiries. We will talk more about this later.
Hard Inquiries vs. Soft Inquiries: What Is the Difference?
Not all credit checks are created equal. The type of inquiry determines whether your credit score takes a hit. Understanding this difference is one of the most important parts of the whole process.
What Is a Hard Inquiry?
A hard inquiry happens when a lender or insurer pulls your full credit report. This type of check is recorded on your credit file and can affect your score. A single hard inquiry typically lowers your score by 5 to 10 points. The impact is usually temporary and fades within a few months. However, multiple hard inquiries in a short period can add up and signal financial stress to other creditors.
When you apply for a new insurance policy, the company may perform a hard inquiry. This is especially common with larger policies or when you are switching providers. Always read the fine print before giving an insurer permission to check your credit.
What Is a Soft Inquiry?
A soft inquiry is a background check that does not affect your credit score at all. Insurers often use soft inquiries to pre-qualify you for a policy or to check your rate. You can also check your own credit through a soft inquiry without any penalty. If you are just comparing car insurance rates online, most quote tools use soft checks, which is great news for your score.
The key takeaway is simple. Soft inquiries are safe. Hard inquiries can cause a small, temporary dip. Always ask the insurer whether the check will be hard or soft before you proceed.
Does Shopping for Car Insurance Hurt Your Credit?
One of the biggest concerns drivers have is whether shopping around for the best deal will damage their credit. The good news is that insurance inquiries are treated differently than loan inquiries. When you shop for car insurance within a short window, typically 14 to 45 days, credit scoring models often group these inquiries together. This means multiple checks for the same purpose count as a single inquiry.
Here are some tips to protect your credit while shopping for insurance:
- Compare quotes within a 30-day window to minimize the impact of hard inquiries.
- Ask the insurer upfront whether they will run a hard or soft credit check.
- Use online comparison tools that only perform soft inquiries for initial quotes.
- Check your own credit report regularly so you know exactly where you stand before applying.
Also, keep in mind that some insurers may check your credit again at renewal time. This is worth knowing so you are not surprised by a score change. Staying on top of your monthly car payment and other financial obligations helps keep your credit stable year-round.
Which States Restrict or Ban Credit-Based Insurance Scoring?
Not every state allows insurers to use credit in their pricing decisions. In fact, several states have passed laws limiting or completely banning the use of credit-based insurance scores. This is an important factor to consider, especially if you live in one of these areas.
Here are the states that have restrictions on using credit for car insurance pricing:
- California — Bans the use of credit-based insurance scores entirely.
- Hawaii — Prohibits credit-based insurance scoring for auto policies.
- Massachusetts — Does not allow insurers to use credit in pricing.
- Michigan — Restricts the use of credit in auto insurance rate calculations.
- Oregon — Has limitations on how credit can be used for insurance pricing.
If you live in one of these states, your credit score has no impact on your car insurance rate. This is a huge advantage and shows how much the rules can vary depending on where you live. If you are moving or considering a policy in a different state, this is definitely worth researching. You can also check with your state insurance department for the latest regulations. Understanding these rules helps you make better decisions when you do you pay car insurance monthly or compare coverage options.
How Your Credit Score Affects Your Insurance Premium
Now that you understand the mechanics, let us talk about the real-world impact. Your credit score can directly influence how much you pay for car insurance. Drivers with excellent credit often pay significantly less than those with poor credit. The difference can be hundreds of dollars per year, which adds up fast.
What Credit Score Do You Need for the Best Rates?
There is no single cutoff, but most insurers consider a FICO score above 670 to be good. A score above 740 is excellent and typically qualifies you for the lowest rates. If your score is below 600, you may face higher premiums or even difficulty getting approved for certain policies. The good news is that improving your credit over time can lead to better insurance rates and lower monthly costs.
Can You Get Car Insurance With Bad Credit?
Yes, you can. Many insurers offer policies for drivers with less-than-perfect credit. However, the premiums will likely be higher. Some companies specialize in high-risk policies and can work with you to find affordable coverage. If you are struggling with credit, focus on building good financial habits. Pay your bills on time, reduce your credit utilization, and avoid opening too many new accounts at once. Over time, your score will improve, and so will your insurance costs.
The Impact of Claims on Your Credit and Insurance
Filing a claim does not directly affect your credit score. However, frequent claims can lead to higher premiums or even non-renewal of your policy. Insurers track your claim history through the Comprehensive Loss Underwriting Exchange (CLUE) database. This is separate from your credit report but still affects your insurance profile. Keeping your claims low and your credit in good shape is the best strategy for long-term savings.
Can You Improve Your Credit to Lower Insurance Costs?
Absolutely. Improving your credit is one of the most effective ways to reduce your car insurance costs. Since insurers use credit as a key factor in pricing, even a small improvement in your score can lead to meaningful savings. Here is how you can start.
Quick Tips to Boost Your Credit Score
- Pay all bills on time. Payment history is the single biggest factor in your credit score. Set up automatic payments or reminders to never miss a due date.
- Reduce your credit card balances. Lowering your credit utilization ratio below 30% can boost your score quickly.
- Check your credit report for errors. Dispute any incorrect information that may be dragging your score down.
- Avoid opening too many new accounts. Each new account creates a hard inquiry and can temporarily lower your score.
- Keep old accounts open. The length of your credit history matters. Closing old accounts can shorten your average account age.
Expert Insights on Credit and Insurance
Insurance experts agree that credit-based scoring is here to stay. While some consumers find it unfair, insurers argue that it provides a more accurate picture of risk. The industry has been using credit information for decades, and regulations vary widely by state. If you are concerned about the impact of insurance checks on your credit, the best approach is to be proactive. Monitor your credit regularly, shop for insurance within a narrow time window, and always ask about the type of credit check before giving consent.
It is also worth noting that some insurers do not use credit at all. If you live in a state where credit scoring is banned, or if you prefer a company that does not check credit, your options are still available. Doing your research before you apply can save you time and protect your score.
Understanding the connection between car insurance and your credit score empowers you to make smarter financial decisions. Whether you are shopping for a new policy or just want to protect your score, being informed is the first step. Take control of your financial health today and enjoy the benefits of lower premiums and better coverage.
Common Mistakes People Make With Insurance and Credit
Avoiding common pitfalls can save you money and protect your credit. Here are some mistakes to watch out for:
- Letting your policy lapse. A lapse in coverage does not directly hurt your credit, but it can lead to fines and higher future premiums.
- Applying for multiple policies at once. Spreading out your applications helps limit the number of hard inquiries on your report.
- Ignoring your credit report. Errors on your credit report can silently increase your insurance costs. Check your report at least once a year.
- Assuming all insurers use credit the same way. Different companies weigh credit factors differently. One company may offer better rates than another even with the same score.
By avoiding these mistakes, you can keep your credit strong and your insurance costs low. A little effort goes a long way toward protecting both your score and your wallet.
Final Thoughts
So, does car insurance affect your credit score? The answer is yes, but the impact depends on the type of credit check and your overall financial situation. Hard inquiries can cause a small, temporary dip, while soft inquiries have no effect. Your credit-based insurance score plays a role in determining your premiums, and improving your credit can lead to real savings. Whether you are paying monthly car insurance or shopping for a new policy, staying informed is your best defense.
Take the time to understand how insurers use your credit. Shop smart, compare quotes within a short window, and keep your financial habits strong. Your credit score and your wallet will thank you. And remember, if you ever need to claim car insurance on taxes or wonder whether all states require car insurance, the rules can vary widely. Always do your homework before making decisions. Knowledge is power, and in this case, it also means savings.
Protecting your credit and managing your insurance wisely go hand in hand. Start today, and you will see the benefits for years to come.
Frequently Asked Questions
Does car insurance affect your credit score directly?
Car insurance does not directly change your credit score. However, when an insurer runs a hard credit check during the application process, it can cause a small, temporary dip. Soft inquiries used for quoting have no impact on your score at all.
What is a credit-based insurance score?
A credit-based insurance score is a special number insurers use to predict your likelihood of filing a claim. It is based on factors like payment history, credit utilization, and length of credit history. It is different from your regular FICO score.
Can I get car insurance with bad credit?
Yes, you can get car insurance with bad credit. Many insurers offer policies for drivers with lower credit scores. However, you may pay higher premiums. Improving your credit over time can help you qualify for better rates.
How long does a hard inquiry from car insurance stay on my credit report?
A hard inquiry typically stays on your credit report for two years. However, its impact on your score usually fades within a few months. The effect is generally small, dropping your score by 5 to 10 points at most.
Are there states where insurers cannot use credit for pricing?
Yes, several states have banned or restricted the use of credit in car insurance pricing. California, Hawaii, and Massachusetts are among the states that do not allow credit-based insurance scoring. Check your state laws for the latest rules.
Will shopping for car insurance quotes hurt my credit?
Shopping for quotes within a short window, usually 14 to 45 days, groups multiple inquiries together as a single check. This minimizes any impact on your credit. Using online comparison tools that only perform soft inquiries is the safest approach.
=== CONCLUSION ===
Car insurance and credit are closely connected, and understanding this relationship puts you in a stronger financial position. A hard inquiry may cause a small dip, but smart shopping habits and good credit management keep the impact minimal. Your credit score influences your premiums, and improving it can save you real money over time. Stay informed, shop wisely, and take control of both your insurance and your credit today.