Does Car Insurance Cover Mechanical Problems And Repairs
Most standard car insurance policies do not cover mechanical problems or breakdowns. Your auto insurance is designed for accidents, theft, and weather damage, not wear-and-tear repairs. However, mechanical breakdown insurance and extended warranties can fill this gap and save you thousands in unexpected vehicle repair costs.
You turn the key in the ignition, and nothing happens. Or worse, your car starts making a strange noise, and the check engine light blinks on. Your first thought? “Does car insurance cover mechanical problems?”
The short answer is usually no. Most standard auto insurance policies do not pay for mechanical failures or breakdowns. But the full story is more nuanced than that. There are options available that can protect you from expensive repair bills. Let us walk through everything you need to know about car insurance and mechanical problems.
Understanding what your policy covers can save you thousands of dollars. It also prevents the frustration of filing a claim only to find out it is not eligible. Whether you drive a new car or a used vehicle, this guide will help you make smart decisions about protecting your ride.
Key Takeaways
- Standard policies exclude mechanical repairs: Liability, collision, and comprehensive coverage do not pay for breakdowns caused by normal wear and tear.
- Mechanical breakdown insurance (MBI) exists: This add-on covers major systems like the engine, transmission, and electrical components after your factory warranty expires.
- Extended warranties are a popular alternative: They work similarly to MBI and are often offered at the time of vehicle purchase.
- Roadside assistance may help in some cases: Towing and jump-starts are sometimes covered, but not the actual repair costs.
- Always read your policy details: Understanding your specific coverage prevents surprise bills and helps you plan for maintenance costs.
- Car insurance rates may rise after a claim: Filing unnecessary claims can increase your premiums without solving mechanical issues.
📑 Table of Contents
- What Does Standard Car Insurance Cover?
- What Is Mechanical Breakdown Insurance?
- Does Car Insurance Cover Repairs After an Accident?
- Can You Add Mechanical Coverage to Your Existing Policy?
- Other Ways to Protect Yourself From Repair Costs
- Common Myths About Car Insurance and Mechanical Repairs
- How to Decide If You Need Mechanical Breakdown Coverage
- Final Thoughts
What Does Standard Car Insurance Cover?
Most drivers carry a basic policy that includes liability coverage, collision coverage, and comprehensive coverage. Each type serves a specific purpose. None of them are designed to handle mechanical failures.
Liability coverage pays for damage you cause to other people or their property. It does not pay for your own vehicle repairs. Collision coverage pays when your car gets damaged in an accident with another vehicle or object. Comprehensive coverage handles non-collision events like theft, vandalism, fire, and weather damage.
So what is the common thread? All of these cover sudden, unexpected events. They do not cover gradual wear and tear. A blown engine from old age, a transmission that fails after 100,000 miles, or brakes that wear out over time are not covered. These are considered maintenance issues, not insurance events.
Why Mechanical Problems Are Excluded
Insurance companies think about risk. A sudden accident is unpredictable. A mechanical failure from age and use is expected. The whole point of insurance is to protect against the unexpected, not the inevitable.
If insurers covered mechanical breakdowns, premiums would skyrocket. Every older car on the road would need coverage for things like worn-out engines and failing transmissions. That is not how the system works.
This is why many drivers look for additional coverage options. Mechanical breakdown insurance and extended warranties exist specifically to fill this gap. They are worth exploring if you want peace of mind beyond your standard policy.
What Is Mechanical Breakdown Insurance?
Mechanical breakdown insurance, often called MBI, is a coverage option that pays for repairs to major vehicle systems. Think of it as insurance for the parts that wear out over time. It is different from your standard auto policy because it focuses on internal failures rather than external damage.
MBI typically covers things like:
- Engine repairs including internal component failures
- Transmission problems such as slipping or complete failure
- Electrical system faults including the starter and alternator
- Cooling system failures like a blown radiator or water pump
- Air conditioning and heating system repairs
MBI is not available everywhere, and not all insurers offer it. It is most commonly available for newer vehicles with low mileage. Usually, you must purchase it within a certain window after buying your car, often within the first year or two.
How MBI Differs From a Warranty
People often confuse mechanical breakdown insurance with a warranty, but they are not the same. A warranty comes with the vehicle from the manufacturer. It covers defects in materials or workmanship for a set period. MBI is an insurance product that you purchase separately.
Here is a quick comparison:
| Feature | Warranty | Mechanical Breakdown Insurance |
|---|---|---|
| Who provides it | Manufacturer or dealer | Insurance company |
| When it starts | From the date of purchase | After factory warranty expires |
| Duration | Usually 3 years or 36,000 miles | Varies by policy |
| Transferable | Sometimes | Depends on the policy |
| Cost | Included in vehicle price | Monthly or one-time premium |
Both options protect you from costly repairs. But they work differently, and understanding the distinction helps you choose the right one for your situation.
Does Car Insurance Cover Repairs After an Accident?
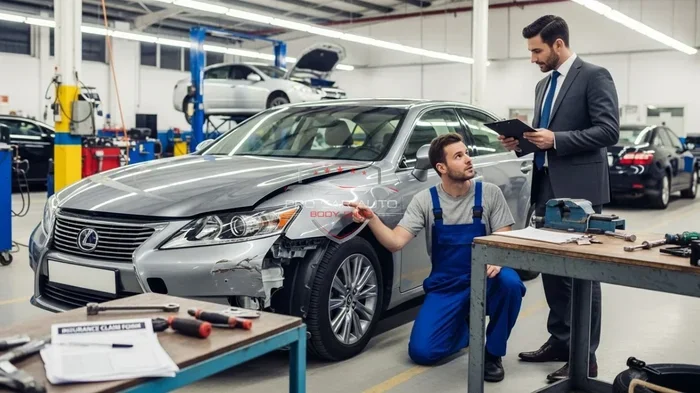
Yes, but only if the mechanical damage results from a covered event. For example, if you get into a fender bender and the collision damages your transmission, your collision coverage should help pay for the repair.
The key difference is the cause. If the transmission failed because of normal wear, your policy will not cover it. If the transmission was damaged in a crash, it becomes a covered repair. This distinction matters a lot when you are dealing with a damaged vehicle.
Here are some scenarios where car insurance would cover a mechanical-type repair:
- A tree falls on your car and damages the engine block
- You hit a deep pothole and bend an axle or suspension component
- Another driver rear-ends you and damages your cooling system
- Flood water enters the engine and causes internal damage
In all these cases, the mechanical damage came from an external event. That is what your insurance is designed to handle. Pure mechanical failures from age or lack of maintenance are not covered.
Can You Add Mechanical Coverage to Your Existing Policy?
Some insurers allow you to add mechanical breakdown insurance as an endorsement to your existing policy. This is often the most convenient way to get coverage for repairs. You do not need to buy a separate policy from a different provider.
Before you add any coverage, consider a few things:
- Check your vehicle age and mileage. Many MBI policies only cover cars under a certain age or with fewer than a set number of miles.
- Review the deductible. Like other insurance products, MBI usually comes with a deductible you must pay before coverage kicks in.
- Compare costs. Get quotes from multiple providers. Sometimes an extended warranty from a third party costs less than an MBI add-on.
- Read the fine print. Understand exactly what is covered and what is excluded. Some policies exclude electronic components or wear items like brakes and tires.
If you are shopping for car insurance, now is the time to ask about MBI options. Not all agents will bring it up, so you need to be proactive. A quick question at your next policy review can save you a lot of money down the road.
Other Ways to Protect Yourself From Repair Costs
Not everyone qualifies for mechanical breakdown insurance. Maybe your car is too old, or your insurer does not offer it. That does not mean you are out of options. Several alternatives can help you manage repair costs.
Extended Warranties
An extended warranty is probably the most common alternative. These plans are offered by dealerships and third-party companies. They cover repair costs for specific systems after your original warranty expires.
Extended warranties can be a smart investment, especially for vehicles known to have expensive repair histories. For example, if you own a Chevy Tahoe or another large SUV, major repairs can easily cost thousands of dollars. An extended warranty can offset those costs significantly.
Just be careful when choosing a plan. Not all extended warranties are created equal. Some have strict limitations, high deductibles, or exclusions that leave you paying out of pocket. Always read the contract thoroughly before signing.
Emergency Funds and Self-Insurance
Some drivers prefer to skip additional coverage and simply save money for repairs. This approach, called self-insurance, works well for people with a solid emergency fund. If you have several thousand dollars set aside, you can handle most mechanical problems without relying on a third party.
The benefit is flexibility. You are not locked into a contract, and you do not pay monthly premiums. The downside is risk. A major engine failure or transmission replacement can cost $5,000 or more. If you do not have that kind of savings, self-insurance can be a gamble.
Roadside Assistance Coverage
While roadside assistance does not cover mechanical repairs, it can help in other ways. Many auto insurance policies offer towing and labor coverage as an add-on. If your car breaks down on the highway, roadside assistance can tow you to a shop and even provide a jump-start or flat tire change.
This type of coverage does not pay for the actual repair. But it can save you from expensive towing fees and get you back on the road faster. It is a small addition that provides real value, especially for older vehicles.
Common Myths About Car Insurance and Mechanical Repairs
There are a lot of misconceptions about what car insurance covers. Let us clear up some of the most common ones.
Myth 1: Full coverage means everything is covered. Full coverage is not a real insurance term. It usually refers to having both collision and comprehensive coverage. Even with both, mechanical failures are excluded.
Myth 2: If the check engine light is on, insurance should pay. A check engine light signals a problem, but it does not make the repair a covered event. Insurance does not pay for diagnostic trouble codes unless they result from a covered accident.
Myth 3: Car insurance rates go down if you have mechanical coverage. Adding MBI or an extended warranty does not affect your standard premiums. These are separate products with separate costs.
Myth 4: You can claim mechanical repairs on your taxes. In most cases, you cannot claim car insurance premiums or repair costs as a tax deduction unless the vehicle is used exclusively for business purposes. Always consult a tax professional before making assumptions.
Myth 5: Older cars do not need mechanical coverage. Older vehicles actually need it more. As cars age, the likelihood of major repairs increases. If you drive a car with over 100,000 miles, understanding your coverage options becomes even more important.
How to Decide If You Need Mechanical Breakdown Coverage
Deciding whether to add mechanical breakdown insurance depends on several factors. There is no one-size-fits-all answer. Here are some things to consider when making your decision.
Your vehicle age and mileage. Newer cars are usually still under factory warranty. You may not need MBI yet. But once the factory warranty expires, the risk of costly repairs increases. If your car is between 3 and 7 years old, MBI can be a smart investment.
Your budget. Can you afford a $3,000 to $7,000 repair bill without financial strain? If the answer is no, some form of mechanical coverage makes sense. If you have a healthy emergency fund, you might skip it.
Your driving habits. Do you put a lot of miles on your car each year? High-mileage drivers face more mechanical issues. If you commute long distances or use your car for work, coverage becomes more valuable.
Your vehicle reliability. Some cars are known for being dependable. Others have a reputation for expensive repairs. Research your specific make and model. If your vehicle has common issues with its engine or transmission, MBI is worth serious consideration.
The cost of the coverage. Compare the premium cost against the potential repair expenses. If an MBI policy costs $100 per year but could save you $5,000 on a transmission replacement, it is a clear win.
Also, keep in mind that car insurance rates vary widely by state and provider. If you live in Florida, for example, you may have different options than drivers in other states. Understanding your local market can help you find the best coverage at the best price.
One more thing to consider is whether you can deduct insurance costs. In some situations, you may be able to claim car insurance on taxes, especially if you use your vehicle for business. This can offset the cost of your premiums and any additional coverage you purchase.
Final Thoughts
Standard car insurance does not cover mechanical problems or repairs. Your policy is there for accidents, theft, and weather events, not for the slow wear and tear of daily driving. But that does not mean you are left unprotected.
Mechanical breakdown insurance, extended warranties, and smart financial planning can all fill the gap. The key is understanding your options and choosing the one that fits your vehicle, your budget, and your risk tolerance.
Take the time to review your current policy today. Ask your insurer about MBI. Research extended warranty options. And make sure you have a plan for handling repairs, whether through coverage or savings. A little preparation now can save you a lot of stress and money later.
Protecting your car means more than just having a policy. It means understanding what that policy does and does not do. With the right coverage in place, you can drive with confidence knowing you are ready for whatever comes your way.
Frequently Asked Questions
Does full coverage car insurance cover mechanical breakdowns?
No. Full coverage refers to collision and comprehensive coverage. Neither pays for mechanical failures caused by wear and tear, age, or lack of maintenance. Mechanical breakdowns are considered maintenance issues, not covered events under standard policies.
What is the difference between mechanical breakdown insurance and an extended warranty?
Both cover major repair costs after the factory warranty expires. The main difference is that MBI is an insurance product from an insurer, while an extended warranty is typically offered by a dealership or third-party company. MBI is often more flexible and may be easier to claim against.
Can I buy mechanical breakdown insurance for an older car?
Most MBI policies are only available for newer vehicles, usually those under 7 years old with fewer than 100,000 miles. For older cars, extended warranties from third-party providers may be your best option. Always check eligibility requirements before purchasing.
Will filing a mechanical repair claim raise my car insurance rates?
Standard policies do not cover mechanical repairs, so you cannot file a claim for them. If you have MBI and file a covered claim, it may or may not affect your rates depending on your insurer. Contact your provider directly to understand how claims impact your premiums.
Does car insurance cover engine failure?
Only if the engine failure results from a covered event like an accident, fire, or flood. An engine that fails due to old age, lack of oil changes, or normal wear is not covered by standard policies. Mechanical breakdown insurance would cover such failures if you have that add-on.
How much does mechanical breakdown insurance cost?
Costs vary widely based on your vehicle, age, mileage, and provider. On average, MBI plans cost between $50 and $150 per year. Some policies also charge a per-visit service fee or deductible. Always get a detailed quote before committing to a plan.