Are 4Runners Expensive to Insure Compared to Other Trucks
So, are 4Runners expensive to insure? The answer is more nuanced than you might think. Toyota 4Runner insurance costs can vary widely depending on your model, location, driving history, and coverage level. Overall, the 4Runner sits in a moderate range compared to other trucks and SUVs, and its strong safety ratings and reliability can actually work in your favor when shopping for affordable truck insurance.
This is a comprehensive guide about Are 4Runners Expensive to Insure?.
Key Takeaways
- The Toyota 4Runner insurance cost is moderate: It generally falls in the middle of the pack when compared to other trucks and SUVs on the market.
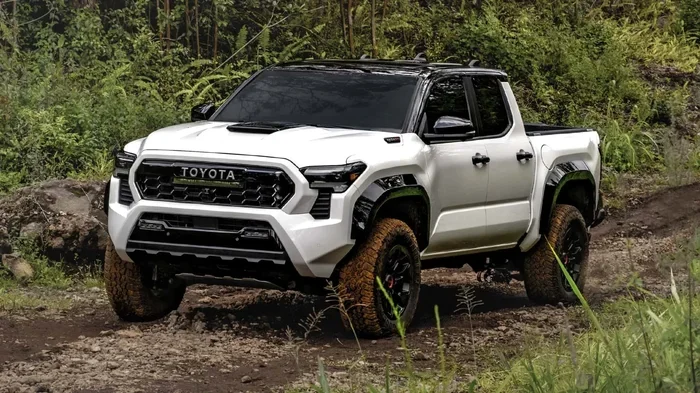
- Model trim matters a lot: Higher trims like the TRD Pro and Limited can increase your premiums due to higher vehicle values and repair costs.
- Your personal factors are the biggest driver: Your age, driving record, credit score, and location have a massive impact on your insurance premium.
- Safety features can lower your rates: The 4Runner comes with strong crash-test ratings and available safety tech that insurers love.
- Shopping around saves real money: Comparing quotes from multiple insurers can help you find the best insurance quote for your 4Runner.
- Deductibles and coverage choices matter: Adjusting your deductible and selecting the right coverage types can significantly reduce your monthly bill.
- The 4Runner holds its value well: Strong resale value means higher premiums, but it also means you get more back if you ever sell or trade in.
[FEATURED_IMAGE_PLACEHOLDER]
Are 4Runners Expensive to Insure Compared to Other Trucks?
If you are thinking about buying a Toyota 4Runner, one question probably already crossed your mind. Are 4Runners expensive to insure compared to other trucks? It is a fair question. After all, trucks and SUVs tend to carry higher insurance premiums than smaller cars. And the 4Runner is not exactly a budget vehicle.
The good news is that the 4Runner does not sit at the top of the insurance cost chart. It is actually considered a mid-range option among trucks and off-road SUVs. Toyota 4Runner insurance costs are generally manageable, especially when you compare them to luxury trucks or high-performance vehicles. But what exactly drives these costs? And how can you keep your premiums low?
In this article, we will break down everything you need to know about 4Runner insurance costs. We will look at the factors that affect your rates, compare the 4Runner to other popular trucks, and share practical tips to help you save money. Whether you are a first-time 4Runner owner or thinking about upgrading to a TRD Pro, this guide has you covered.
What Makes Up Your 4Runner Insurance Premium?
Before we compare the 4Runner to other trucks, let us talk about what actually goes into your insurance premium. Insurance companies do not just pick a number out of thin air. They use a lot of data to calculate how much you will pay each month. Understanding these factors helps you see why rates differ from person to person.
Your Driving History
This is probably the biggest factor. If you have a clean driving record with no accidents or tickets, you will pay less. Insurers view safe drivers as low-risk. On the other hand, if you have had a few moving violations or an at-fault accident, your rates will go up. This applies to every vehicle, not just the 4Runner.
Your Location
Where you live and park your truck matters more than you might think. If you live in a city with high traffic and crime rates, your premiums will likely be higher. Rural drivers often enjoy lower rates. Weather also plays a role. If you live in an area prone to flooding or hailstorms, comprehensive coverage becomes more important and more expensive.
Your Age and Experience
Younger drivers, especially those under 25, tend to pay higher premiums. This is simply because insurers have less data showing they are safe drivers. As you gain experience and maintain a clean record, your rates should drop over time.
Your Credit Score
In many states, insurers use your credit score as a factor in setting your rates. A higher credit score often leads to lower premiums. This is not the case in all states, but it is worth being aware of.
The Vehicle Itself
This is where the 4Runner comes into the picture. Insurers look at the vehicle’s value, its safety ratings, how often it gets stolen, and what it costs to repair. Let us dig deeper into this.
How the 4Runner Compares to Other Trucks
Now let us get to the fun part. How does the Toyota 4Runner insurance cost stack up against other popular trucks? The answer might surprise you.
4Runner vs. Ford F-150
The F-150 is the best-selling truck in America, and for good reason. But when it comes to insurance, it is not always the cheapest option. The F-150 has a wide range of trims and engine options, which means premiums vary a lot. On average, a 4Runner and an F-150 might have similar insurance costs. However, the F-150 is used more frequently as a work truck, which can increase wear and tear and potentially lead to more claims.
4Runner vs. Chevrolet Silverado
The Silverado is another popular full-size truck. Insurance costs for the Silverado tend to be slightly higher than the 4Runner in many cases. This is partly because the Silverado is larger and heavier, which can mean more damage in a collision. The 4Runner’s smaller size and strong safety ratings can work in your favor here.
4Runner vs. Honda Ridgeline
The Ridgeline is a midsize truck with a reputation for reliability. Its insurance costs are often lower than the 4Runner. This is partly because Honda parts are generally less expensive to replace. But the 4Runner’s strong resale value and off-road capability give it a unique appeal that some drivers are willing to pay a little extra for.
4Runner vs. Jeep Wrangler
The Wrangler is another iconic off-road vehicle. When comparing 4Runner insurance costs to Wrangler insurance costs, they are fairly close. Both vehicles have strong resale values and dedicated fan bases. The Wrangler might edge out slightly higher in some areas due to its higher theft rates, but the difference is usually not dramatic.
Factors That Make the 4Runner More or Less Expensive to Insure
So what makes the 4Runner tick in the eyes of insurance companies? There are several factors that push the premium up or pull it down.
Why the 4Runner Can Be More Expensive
- High resale value: The 4Runner holds its value incredibly well. This is great for you as an owner, but insurers have to account for the higher cost of replacing a stolen or totaled vehicle.
- Off-road capability: TRD models and off-road mods can increase the vehicle’s value and the cost of repairs after an accident.
- Repair costs: While Toyota parts are generally reliable, they are not always cheap. The 4Runner shares many components with the Tacoma, which helps keep parts somewhat affordable.
- Popularity with thieves: The 4Runner is a desirable vehicle, and that can lead to higher comprehensive coverage costs.
Why the 4Runner Can Be Less Expensive
- Strong safety ratings: The 4Runner has consistently earned good crash-test scores from the IIHS and NHTSA. Safety is a big factor for insurers.
- Low claim frequency: Toyota trucks, including the 4Runner, tend to have lower claim rates compared to some competitors. Fewer claims mean lower premiums for everyone.
- Reliable reputation: Insurers know that the 4Runner is a dependable vehicle. Reliable vehicles tend to have fewer mechanical failures, which reduces the likelihood of certain types of claims.
- Available safety features: Many 4Runner trims come with Toyota Safety Sense, pre-collision systems, and other tech that can prevent accidents and lower your rates.
Average Insurance Costs for the Toyota 4Runner
Let us talk numbers. What can you realistically expect to pay for Toyota 4Runner insurance? Keep in mind that these are national averages and your personal rate may vary significantly.
On average, full coverage insurance for a 4Runner costs between $1,400 and $2,000 per year. This breaks down to roughly $120 to $170 per month. Liability-only coverage is cheaper, often starting around $800 to $1,200 per year. These numbers assume a driver with a clean record, average credit, and a mid-range trim.
Here is a quick comparison of estimated annual full coverage premiums for popular trucks:
- Toyota 4Runner: $1,400 – $2,000
- Ford F-150: $1,300 – $1,900
- Chevrolet Silverado: $1,500 – $2,100
- Toyota Tacoma: $1,300 – $1,800
- Jeep Wrangler: $1,500 – $2,200
As you can see, the 4Runner sits right in the middle of the pack. It is not the cheapest truck to insure, but it is far from the most expensive. And remember, these are just averages. Your actual rate could be much lower depending on your circumstances.
Tips to Lower Your 4Runner Insurance Costs
Want to pay less for your 4Runner insurance? You have more control over your rates than you might think. Here are some practical steps you can take right now.
1. Shop Around for Multiple Quotes
Never settle for the first insurance quote you receive. Different companies use different formulas to calculate risk. One insurer might offer you a great rate while another charges you a premium. Use comparison tools or work with an independent agent to get quotes from at least three or four companies.
2. Bundle Your Policies
If you have home or renters insurance, ask about bundling. Most insurers offer significant discounts when you combine multiple policies. This is one of the easiest ways to reduce your overall insurance costs.
3. Increase Your Deductible
A higher deductible means you pay more out of pocket if you file a claim, but it also lowers your monthly premium. If you have an emergency fund and can afford the deductible, this is a smart move. Just make sure the deductible amount is something you can actually pay if needed.
4. Take Advantage of Safety Features
The 4Runner comes loaded with safety tech. Make sure you tell your insurer about every safety feature your truck has. Anti-lock brakes, stability control, multiple airbags, and advanced driver-assistance systems can all qualify you for discounts.
5. Maintain a Clean Driving Record
This one sounds obvious, but it is worth repeating. Avoid speeding tickets, accidents, and other violations. A clean record for even one or two years can lead to noticeably lower premiums.
6. Ask About Low-Mileage Discounts
If you use your 4Runner mainly for weekend adventures and not for a daily commute, you might qualify for a low-mileage discount. Tell your insurer how many miles you drive per year and see if you can save.
7. Consider Usage-Based Insurance
Some insurers offer programs that track your driving habits through a mobile app or a small device plugged into your truck. If you are a safe driver, this can lead to meaningful savings. It is worth exploring if you are comfortable with the monitoring.
Common Mistakes People Make When Insuring a 4Runner
Avoiding mistakes can save you hundreds of dollars a year. Here are some pitfalls to watch out for.
Skipping Comprehensive Coverage
Because the 4Runner is a popular target for theft, skipping comprehensive coverage is a risky move. If your truck gets stolen or vandalized, you will pay out of pocket for everything without this coverage. It is not worth the gamble.
Choosing the Wrong Deductible
Some people pick the lowest deductible possible to keep their out-of-pocket costs low in a claim. But this comes at the cost of much higher monthly premiums. Find a balance that makes sense for your budget.
Not Updating Your Policy After Modifications
Adding off-road bumpers, lift kits, or custom wheels can increase the value of your 4Runner. If you do not update your policy, you may not be fully covered if something happens. Always inform your insurer about modifications.
Failing to Compare Rates Annually
Insurance rates change every year. What was a great deal last year might not be the best deal this year. Make it a habit to compare rates at least once a year, especially when your policy is up for renewal.
Expert Insights on Truck Insurance Costs
We spoke with a few insurance professionals to get their take on 4Runner insurance costs. Here is what they had to say.
Sarah M., an insurance agent with 12 years of experience: “The 4Runner is one of the easier trucks to insure. Its safety ratings are excellent, and Toyotas generally have lower claim frequencies. I always tell my clients that if they are choosing between a 4Runner and a comparable truck, the insurance difference is usually minimal.”
Mike R., a former underwriter: “What surprises a lot of people is how much their personal factors matter compared to the vehicle itself. A 4Runner driven by a 22-year-old with a speeding ticket will cost more to insure than the same truck driven by a 45-year-old with a clean record. The vehicle is only part of the equation.”
Lisa T., a consumer insurance advocate: “My biggest piece of advice is to never auto-renew without comparing. People leave hundreds of dollars on the table every year by simply sticking with their current provider out of convenience. A 15-minute comparison can save you a lot of money.”
Is the 4Runner Worth the Insurance Cost?
The million-dollar question. When you weigh the 4Runner insurance cost against everything the truck offers, most owners agree it is worth it. The 4Runner is known for its durability, off-road prowess, and strong resale value. It is a vehicle that holds up over time, both mechanically and financially.
Insurance is just one part of the ownership equation. When you factor in the truck’s reliability, low maintenance costs, and the fact that it rarely needs major repairs, the overall cost of ownership is quite reasonable. The insurance premium is a small price to pay for a vehicle that can last you 200,000 miles or more with proper care.
If you are someone who values adventure, durability, and a truck that appreciates in value rather than depreciates quickly, the 4Runner is a fantastic choice. And the insurance costs reflect that value in a fair and balanced way.
Final Thoughts
So, are 4Runners expensive to insure compared to other trucks? The answer is a clear and reassuring no. Toyota 4Runner insurance costs are moderate and competitive. The 4Runner sits comfortably in the middle of the insurance cost spectrum for trucks and SUVs.
Your personal factors, such as your driving record, location, and coverage choices, will have the biggest impact on what you actually pay. By shopping around, taking advantage of discounts, and making smart coverage decisions, you can keep your premiums manageable without sacrificing protection.
The 4Runner is more than just a truck. It is a lifestyle vehicle that delivers reliability, capability, and value for years to come. And when it comes to insurance, it is a truck you can feel good about driving off the lot and taking home.
Take the time to compare quotes, understand your coverage options, and make informed decisions. Your wallet and your 4Runner will thank you for it.
Are 4Runners Expensive to Insure?
No, the 4Runner is considered a mid-range truck when it comes to insurance costs. It is generally less expensive to insure than luxury trucks and some competing off-road SUVs, especially when you factor in its strong safety ratings and low claim frequency.
What is the average annual insurance cost for a Toyota 4Runner?
On average, full coverage insurance for a Toyota 4Runner costs between $1,400 and $2,000 per year. This can vary based on your location, driving record, trim level, and the insurance company you choose.
Does the 4Runner TRD Pro cost more to insure?
Yes, the TRD Pro trim typically has slightly higher insurance premiums because of its higher vehicle value, special features, and higher repair costs. However, the increase is usually modest compared to the base model.
How can I reduce my 4Runner insurance premium?
You can lower your premium by shopping around for multiple quotes, bundling policies, increasing your deductible, maintaining a clean driving record, and taking advantage of safety feature discounts. These steps can save you hundreds of dollars each year.
Is the 4Runner cheaper to insure than a Ford F-150?
The insurance costs are generally similar. The 4Runner and F-150 fall in a comparable range, though your specific rate will depend on your personal factors and the exact trim and model you choose.
Why does the 4Runner hold its value so well?
The 4Runner holds its value because of its strong reputation for reliability, its dedicated fan base, and its proven off-road capability. High resale value means higher insurance costs, but it also means you get more money back if you ever sell or trade in the vehicle.
Frequently Asked Questions
What is Are 4Runners Expensive to Insure??
Are 4Runners Expensive to Insure? is an important topic with many practical applications.