What Is the Average Cost of Car Insurance in New York
Car insurance in New York costs an average of $2,200 to $2,800 per year, making it one of the more expensive states for auto coverage. Your New York auto insurance rate depends on factors like your zip code, driving record, age, and the type of car you drive. Shopping around and taking advantage of available discounts can help you lower your car insurance premium significantly.
If you live in New York or are thinking about moving there, one thing is for sure: you need to budget for car insurance. The cost of car insurance in New York is among the highest in the entire country. But what exactly drives these prices, and what can you do to pay less? This guide breaks everything down in plain, simple terms.
Whether you are a new driver, a longtime New Yorker, or just shopping for a better rate, you are in the right place. We will walk through average costs, the factors that shape your price, the coverage types you need, and practical tips to save money. Let us dive in.
Key Takeaways
- Average annual cost: New York drivers pay between $2,200 and $2,800 per year for car insurance.
- Zip code matters: Your location within New York can raise or lower your rates by hundreds of dollars.
- Minimum coverage is not enough: New York requires specific liability limits, and full coverage costs more but offers better protection.
- Discounts are widely available: Safe driving, bundling policies, and loyalty can all reduce your car insurance rates.
- Rates are rising: Car insurance rates in New York have been climbing, so reviewing your policy annually is essential.
- Comparison shopping pays off: Getting multiple insurance quotes can save you hundreds of dollars each year.
📑 Table of Contents
- What Is the Average Cost of Car Insurance in New York?
- Factors That Affect Your Car Insurance Rates in New York
- New York Car Insurance Requirements
- How to Save Money on Car Insurance in New York
- Are Car Insurance Rates Rising in New York?
- Finding the Right Car Insurance Policy for You
- Common Mistakes New York Drivers Make with Car Insurance
- Final Thoughts on Car Insurance Costs in New York
What Is the Average Cost of Car Insurance in New York?
The average cost of car insurance in New York sits around $2,200 to $2,800 per year. That works out to roughly $185 to $235 per month. These numbers come from a mix of full coverage policies across different driver profiles and zip codes.
To put that in perspective, the national average for car insurance is around $1,700 per year. So New York drivers pay roughly 30% more than the rest of the country. The state’s dense population, high traffic volume, and frequent claims all contribute to these higher prices.
But here is the thing: averages do not tell your whole story. Your personal rate could be much lower or much higher depending on your situation. A 45-year-old driver with a clean record in upstate New York will pay far less than a 20-year-old driver in the Bronx. More on that below.
Factors That Affect Your Car Insurance Rates in New York
Insurance companies use a lot of data to set your price. Understanding these factors helps you see why your rate is what it is and what you can do to change it.
Your Location Within New York
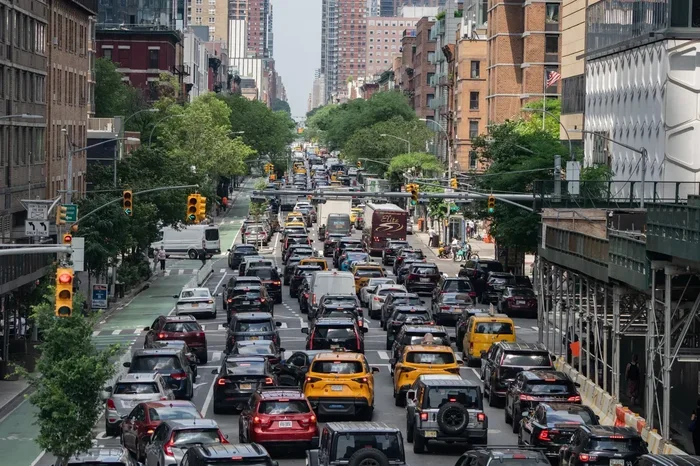
Where you live has a huge impact on your car insurance rates. Dense urban areas like New York City, Brooklyn, and Queens see more accidents, thefts, and vandalism. Because of that, insurers charge higher premiums in these areas.
Rural areas and smaller towns in upstate New York generally have lower rates. Your specific zip code matters more than you might think. Two drivers living just a few miles apart can see very different prices.
Your Age and Driving Experience
Younger drivers, especially those under 25, pay the highest rates. Inexperience on the road leads to more accidents, and insurers price that risk into your premium. As you gain driving experience and get older, your rates typically drop.
Drivers in their 40s and 50s usually enjoy the lowest rates. After age 65, rates may start creeping back up due to slower reaction times and higher accident risk among older drivers.
Your Driving Record
A clean driving record is your best friend when it comes to car insurance rates. Speeding tickets, accidents, and DUI convictions all signal risk to insurers. Even a single at-fault accident can raise your premium by 20% to 40%.
Tickets and violations typically stay on your record for three to five years. Once they drop off, you should see your rates go down. Maintaining safe driving habits over time is one of the most effective ways to keep your costs low.
The Type of Vehicle You Drive
Your car matters more than you might think. A brand-new luxury SUV costs more to insure than a reliable used sedan. Insurers look at the vehicle’s value, repair costs, safety ratings, and theft risk.
Cars with advanced safety features like automatic braking and lane assist may qualify for discounts. On the flip side, high-performance vehicles and models with high theft rates will cost more to insure.
Your Coverage Levels and Deductible
The amount of coverage you choose directly affects your premium. Full coverage car insurance includes comprehensive and collision on top of liability. It costs more than basic liability-only coverage, but it protects you financially if you are at fault in an accident.
Your deductible also plays a role. A higher deductible means you pay more out of pocket if you file a claim, but it lowers your monthly premium. Finding the right balance is key to managing your car insurance premium.
New York Car Insurance Requirements
New York is a no-fault insurance state, which means something specific for how claims work after an accident. Understanding the state’s requirements helps you make sure you are properly covered and not paying for coverage you do not need.
Minimum Liability Coverage in New York
New York law requires all drivers to carry a minimum level of liability coverage. The state mandates the following limits:
- Bodily injury liability: $25,000 per person and $50,000 per accident
- Property damage liability: $10,000 per accident
- No-fault personal injury protection (PIP): $50,000 per person
- Uninsured motorist coverage: $25,000 per person and $50,000 per accident
These minimums provide a basic level of protection, but they may not be enough in a serious accident. Medical bills and vehicle repairs can quickly exceed these limits, leaving you responsible for the difference out of pocket.
Why Minimum Coverage May Not Be Enough
Many experts recommend carrying well above the state minimums. In New York City, even a minor fender bender can result in thousands of dollars in costs. Full coverage car insurance gives you a much stronger safety net.
If you have a loan or lease on your vehicle, your lender will likely require full coverage anyway. Even if your car is paid off, the financial risk of carrying only minimum coverage in a state like New York is significant.
Do You Need Gap Insurance?
Gap insurance covers the difference between what you owe on your car loan and the vehicle’s actual cash value if it is totaled. This type of coverage is especially important if you have a small down payment or a long loan term.
Many drivers wonder whether gap insurance is worth it. The answer depends on your loan balance, your vehicle’s depreciation rate, and your financial situation. If you owe more than your car is worth, gap insurance can save you from a serious financial hit.
How to Save Money on Car Insurance in New York
High insurance costs do not have to break the bank. There are many practical steps you can take to reduce your car insurance premium and keep more money in your pocket.
Shop Around and Compare Quotes
The single best way to find affordable coverage is to compare quotes from multiple insurers. Each company uses its own formula to set rates, so the same driver can get very different prices from different companies.
You can get insurance quotes online in just a few minutes. Do not just go with the first company you find. Get at least three or four quotes and compare them side by side. The savings can be substantial.
Take Advantage of Available Discounts
Most insurers offer a range of discounts that can lower your bill. Here are some of the most common ones:
- Safe driver discount: For drivers with no accidents or violations
- Bundling discount: When you combine car and home insurance
- Good student discount: For students maintaining a B average or higher
- Low mileage discount: If you drive fewer than 7,500 miles per year
- Defensive driving course discount: Completing an approved course
- Loyalty discount: For staying with the same insurer over time
Ask your insurer about every discount they offer. You may be qualifying for savings you did not even know about.
Raise Your Deductible
Choosing a higher deductible is one of the simplest ways to lower your premium. If you increase your comprehensive and collision deductibles from $500 to $1,000, you could see a noticeable drop in your monthly cost.
Just make sure you can afford the higher deductible if you ever need to file a claim. This strategy works best for drivers who have an emergency fund set aside.
Maintain a Good Credit Score
In many states, insurers use credit-based insurance scores to help set rates. New York is one of the states where this practice is allowed. A higher credit score generally leads to lower insurance premiums.
Pay your bills on time, keep your credit utilization low, and avoid opening too many new accounts at once. Over time, these habits can improve your score and your insurance rates.
Review Your Policy Regularly
Your insurance needs change over time. If your car is paid off, you may not need the same level of coverage. If you have moved to a safer neighborhood, your rates may go down.
Make it a habit to review your policy at least once a year. Car insurance rates change frequently, and what you paid last year may not be the best deal available today. Regular reviews help you catch savings opportunities you might otherwise miss.
Are Car Insurance Rates Rising in New York?
The short answer is yes. Car insurance rates across the country have been climbing, and New York is no exception. Several trends are driving this increase.
Inflation has raised the cost of vehicle repairs and medical care. More people on the road means more accidents. Severe weather events and infrastructure challenges also contribute to rising claims. On top of all that, the rising cost of vehicle technology, especially in newer cars with advanced driver assistance systems, makes repairs more expensive.
These trends mean that what you pay today may be higher than what you paid even a year or two ago. Staying informed and actively managing your policy is more important than ever.
What You Can Do About Rising Rates
The best defense against rising rates is proactive management. Shop around every renewal period. Ask about discounts. Consider raising your deductible if your financial situation allows it. And never be afraid to switch insurers if you find a better rate.
Being a loyal customer is nice, but staying loyal to an overpriced policy does not make sense. The insurance market is competitive, and there is almost always a better deal available if you look.
Finding the Right Car Insurance Policy for You
Choosing the right policy is about balancing cost, coverage, and peace of mind. The cheapest option is not always the best if it leaves you underinsured. Here is how to approach the decision.
Evaluate Your Personal Risk Profile
Think about your driving habits, your vehicle, and your financial situation. Do you commute long distances in heavy traffic? Do you live in a high-theft area? Do you have significant assets that could be at risk in a lawsuit?
Your answers to these questions help you determine how much coverage you actually need. A driver with a short commute and an older car may be fine with minimum coverage. A driver with a new car and a long commute should consider full coverage.
Understand the Different Types of Coverage
Beyond the state-required minimums, there are several coverage types worth considering:
- Collision coverage: Pays for damage to your car in an accident you cause
- Comprehensive coverage: Covers non-accident damage like theft, fire, and weather
- Uninsured/underinsured motorist coverage: Protects you if the other driver has no or insufficient insurance
- Medical payments coverage: Covers medical bills for you and your passengers regardless of fault
- Rental car reimbursement: Pays for a rental while your car is being repaired
Not every driver needs all of these. But understanding what each one does helps you make informed decisions about your car insurance in New York.
Get Multiple Quotes Before You Decide
Never buy a policy without comparing at least three quotes. The difference between the cheapest and the most expensive policy for the same driver can be hundreds of dollars per year.
You can get insurance quotes directly from insurance company websites, through independent comparison sites, or by working with an insurance broker. Each method has its advantages, and the best approach is to use a combination of them.
If you are currently paying for car insurance, it is worth checking whether you could get a better rate elsewhere. The process takes just a few minutes, and the potential savings are well worth the effort.
Common Mistakes New York Drivers Make with Car Insurance
Avoiding these common pitfalls can save you money and ensure you are properly protected.
- Auto-renewing without shopping around: Loyalty does not pay when your insurer keeps raising your rates.
- Choosing coverage based on price alone: The cheapest policy may not offer adequate protection.
- Not understanding no-fault insurance: Many New York drivers do not fully understand how the no-fault system works and what it means for their claims.
- Dropping coverage on an old car: Even older cars have value, and being uninsured is a huge financial risk.
- Forgetting to update your policy: Life changes like moving, getting married, or buying a new car should trigger a policy review.
Final Thoughts on Car Insurance Costs in New York
The average cost of car insurance in New York is high compared to the rest of the country, but that does not mean you have to overpay. By understanding the factors that drive your rates, shopping around for the best insurance quotes, and taking advantage of every discount available, you can find coverage that fits your budget and your needs.
Review your policy at least once a year. Stay informed about rate trends. And never be afraid to switch insurers if you find a better deal. Your wallet will thank you.
Car insurance is one of those necessary expenses that everyone needs but nobody loves. The good news is that with a little effort and the right approach, you can manage your costs effectively and drive with confidence knowing you have the right protection in place.
Frequently Asked Questions
What is the cheapest car insurance in New York?
The cheapest car insurance in New York varies by driver, but companies like GEICO, Progressive, and State Farm often offer competitive rates. Your personal rate depends on your age, driving record, location, and vehicle. Always compare multiple quotes to find the best deal.
How much is full coverage car insurance in New York per month?
Full coverage car insurance in New York typically costs between $185 and $280 per month. The exact price depends on your profile and coverage limits. Drivers with clean records and older vehicles usually pay toward the lower end of that range.
Does where I live in New York affect my insurance rates?
Yes, your location has a major impact on your car insurance rates. Dense urban areas like Manhattan and Brooklyn have higher premiums due to traffic, theft, and accident risk. Rural areas and upstate locations generally have lower rates.
Do I need uninsured motorist coverage in New York?
New York requires uninsured motorist coverage as part of its minimum insurance requirements. This coverage protects you if you are in an accident caused by a driver with no insurance or insufficient insurance. It is a smart safeguard even if you are a careful driver.
How can I lower my car insurance premium in New York?
You can lower your car insurance premium by shopping around for quotes, taking advantage of discounts, raising your deductible, maintaining a clean driving record, and improving your credit score. Even small changes can lead to meaningful savings over time.
Are car insurance rates in New York going up?
Yes, car insurance rates in New York have been rising due to inflation, increased repair costs, and higher accident frequency. Staying informed and regularly reviewing your policy helps ensure you are not overpaying as rates change.