Does Car Insurance Cover Windshield Damage Right Now
Does car insurance cover windshield damage? The short answer is yes — if you have comprehensive coverage. Most full auto insurance policies include glass protection, but the details matter. Your insurance deductible, type of policy, and the kind of damage all play a role in what you pay out of pocket. This guide breaks down everything you need to know about filing a claim, windshield replacement cost, and how to keep your auto insurance policy working for you.
This is a comprehensive guide about Does Car Insurance Cover Windshield Damage.
Key Takeaways
- Comprehensive coverage is key: It typically covers windshield damage from rocks, debris, weather, and vandalism.
- Collision coverage usually does not: It only covers damage from accidents, not standalone glass issues.
- Deductibles vary: Some insurers offer a zero-deductible glass option that saves you money.
- Claims can affect rates: Filing a glass claim may impact your insurance premium depending on your provider.
- Small cracks can be repaired: Not all damage requires a full replacement — quick fixes save money.
- Prevention helps: Simple habits like avoiding tailgating reduce the risk of windshield crack damage.
[FEATURED_IMAGE_PLACEHOLDER]
Does Car Insurance Cover Windshield Damage Right Now?
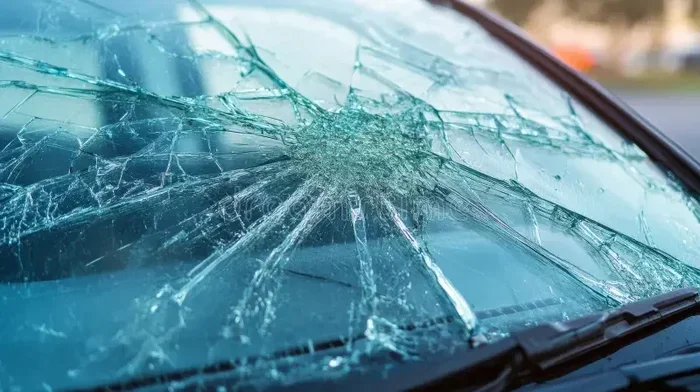
Your windshield takes a beating every time you drive. Rocks fly up from trucks. Hail strikes without warning. A stray branch falls during a storm. And just like that, you have a crack or chip right in your line of sight.
So the big question is simple: does car insurance cover windshield damage? The answer depends on your auto insurance policy, the type of coverage you carry, and the cause of the damage. But here is the good news — most drivers are more protected than they think.
This article walks you through every angle of windshield damage coverage. You will learn what types of insurance pay for glass repairs, how much you might pay out of pocket, and the exact steps to get your windshield fixed without stress.
Whether you have a tiny chip or a long crack running across the glass, understanding your insurance coverage limits is the first step to making the right decision. Let us get into it.
What Types of Insurance Cover Windshield Damage?
Not all car insurance is the same. Some policies pay for glass damage. Others do not. Understanding the difference between coverage types is essential before you file anything.
Comprehensive Coverage
Comprehensive coverage is the main player when it comes to windshield damage. This type of insurance covers damage that is not caused by a collision. Think of it as protection from the unexpected.
Here are common scenarios covered by comprehensive insurance:
- Rock and debris hits: Stones kicked up by other vehicles on highways.
- Hail storms: Ice damage that creates multiple dings or cracks.
- Vandalism: Someone intentionally breaks or cracks your glass.
- Falling objects: Tree branches, furniture, or other items that land on your windshield.
- Weather damage: Heavy rain, wind-blown debris, and extreme temperature changes.
Comprehensive coverage is not required by law in most states. However, if you finance or lease your vehicle, your lender will almost certainly require it. It is one of the most affordable add-ons you can get on your auto insurance policy.
Collision Coverage
Collision coverage pays for damage caused by an accident with another vehicle or object. But here is the catch — it generally does not cover standalone windshield damage.
If you swerve to avoid a pothole and crack your windshield, collision coverage may step in. But if a rock hits your glass while you are driving straight, that is comprehensive territory.
Think of it this way:
- Comprehensive = damage from non-accident events.
- Collision = damage from actual crashes or rollovers.
Liability Coverage
Liability insurance covers damage you cause to other people and their property. It does not cover your own windshield. If another driver hits your car and cracks your windshield, their liability coverage should pay for your repairs.
But if you are at fault, your own liability policy will not help with your glass. This is why carrying comprehensive coverage is so important for your own protection.
How Much Does Windshield Repair and Replacement Cost?
Understanding the cost side helps you decide whether to file a claim or pay out of pocket. Windshield replacement cost can vary widely based on several factors.
Average Costs for Windshield Repair
Small chips and cracks that are under three inches usually qualify for repair. The cost for a simple fix is surprisingly low:
- Chip repair: $50 to $150
- Small crack repair: $75 to $200
- Multiple repairs: $150 to $300
Many insurance companies cover the full cost of a repair with comprehensive coverage, especially if you have a zero-deductible glass option. This means you pay nothing out of pocket.
Average Costs for Windshield Replacement
When the damage is too severe for repair, a full replacement is needed. Here is what you can expect:
- Standard aftermarket glass: $150 to $350
- OEM (Original Equipment Manufacturer) glass: $350 to $800 or more
- Premium vehicles or luxury brands: $500 to $1,200+
The price difference between aftermarket and OEM glass is significant. OEM glass matches the original factory quality, while aftermarket glass is a compatible replacement. Your insurance policy may cover one or both, so it is worth checking before you approve the work.
Factors That Affect the Price
Several things influence how much you will pay for auto glass repair or replacement:
- Vehicle make and model: Luxury and rare vehicles cost more to fix.
- Type of glass: OEM vs. aftermarket makes a big difference.
- Location: Labor costs vary by region and shop.
- Advanced features: Rain sensors, lane departure warnings, and heated windshields add to the cost.
- Insurance deductible: Your chosen deductible directly impacts your out-of-pocket expense.
How Does the Claims Process Work for Windshield Damage?
Filing a claim for windshield crack damage is simpler than most people expect. Here is a step-by-step look at how it works.
Step 1: Document the Damage
Before you do anything else, take clear photos of the damage from multiple angles. Capture the full scope of the crack or chip. Also note the date, time, and location where the damage occurred. This documentation supports your car insurance claim and speeds up the process.
Step 2: Contact Your Insurance Provider
Call your insurance company or use their app to start a claim. Have your policy number, vehicle details, and photos ready. Most insurers have 24/7 claims support, so you can file at any time.
Step 3: Get an Estimate
Your insurer may direct you to an approved repair shop. They will assess the damage and provide an estimate. Some companies allow you to choose your own shop, while others require you to use a network provider.
Step 4: Pay Your Deductible
If your policy has a deductible, you will pay that amount before insurance covers the rest. For example, if your deductible is $500 and the replacement costs $600, you pay $500 and the insurer pays $100.
However, many insurers now offer zero-deductible glass coverage as an add-on. This means you pay nothing for windshield repairs or replacements. It is worth asking about this option.
Step 5: Get the Repair or Replacement Done
Once the estimate is approved, the shop performs the work. If the damage is repairable, the process usually takes under an hour. A full replacement typically takes one to two hours.
Will Filing a Claim Affect Your Rates?
This is one of the most common concerns drivers have. The answer is: it depends. A single glass claim under comprehensive coverage is less likely to raise your rates than a collision claim. Many insurers treat glass claims as a separate category.
That said, multiple claims over a short period can still trigger a rate increase. If you are deciding whether to file, consider the cost of the repair versus the potential rise in your insurance premium. Sometimes paying out of pocket makes more sense for small repairs.
Quick Tips to Prevent Windshield Damage
Prevention is always better than repair. While you cannot avoid every rock or hailstone, these simple habits reduce your risk of windshield crack and chip damage.
- Keep a safe distance from trucks: Large vehicles kick up the most debris. Stay at least three to four seconds behind them.
- Avoid driving behind construction vehicles: Gravel trucks and dump trucks are notorious for throwing rocks.
- Park in covered areas: Garages and carports protect your glass from hail, falling branches, and bird droppings.
- Replace worn wiper blades: Damaged wipers can scratch your windshield over time. Check them every six months.
- Do not blast your AC on high immediately: Extreme temperature changes can weaken existing chips and cause them to spread. Gradually cool your car instead.
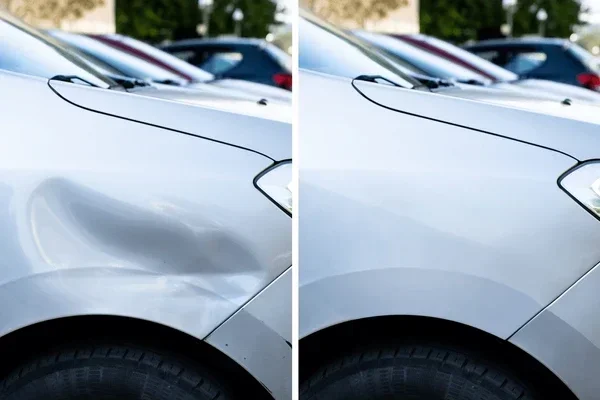
- Fix small chips quickly: A tiny chip can spread into a large crack from vibration and temperature changes. Address minor damage right away.
- Apply a windshield sun shade: Reducing heat buildup on your glass helps prevent stress cracks, especially in hot weather.
How To Remove Ice From Car Glass Safely
Winter weather is tough on windshields. Using the wrong tools or methods can cause cracks and chips to spread. Always use an ice scraper designed for auto glass. Never pour hot water on a frozen windshield — the sudden temperature change can cause the glass to crack.
For stubborn ice, use a de-icing spray or a mixture of water and isopropyl alcohol. These melt ice quickly without damaging your glass. If you want more details on safe ice removal, check out our guide on how to remove ice from car glass for expert tips.
Common Mistakes Drivers Make With Windshield Claims
Avoid these pitfalls to get the best outcome from your auto insurance policy:
- Waiting too long to file: Delaying a claim can complicate things, especially if the damage worsens over time. File as soon as possible.
- Ignoring small chips: A small chip today can become a long crack tomorrow. Repairing early saves money and prevents the need for a full replacement.
- Choosing the wrong glass type: Always ask your insurer whether they cover OEM or aftermarket glass. Choosing OEM without checking coverage can lead to surprise bills.
- Not checking your deductible: Before filing, confirm your deductible amount. If the repair cost is close to your deductible, paying out of pocket might be smarter.
- Assuming all damage is covered: Wear and tear, pre-existing damage, and damage from intentional acts are usually not covered. Know what your policy excludes.
- Not getting multiple quotes: Even if your insurer recommends a shop, getting a second opinion on the cost is always a good idea.
Does Filing a Glass Claim Affect Your Insurance Rates?
Many drivers worry that filing a windshield damage claim will cause their insurance rates to spike. Here is what you need to know.
In most cases, a single comprehensive glass claim does not significantly impact your premium. Insurance companies view glass damage as a common and relatively low-cost event. They treat it differently from at-fault accidents or DUI claims.
However, there are exceptions:
- Multiple claims in a short period: Filing several claims within a year raises a red flag for insurers.
- At-fault glass claims: If your insurer determines you were at fault (for example, you hit a debris pile), it may affect your rates.
- Your insurer’s policies vary: Some companies are more forgiving than others. Always ask your provider directly about their claims impact policy.
If you are unsure whether to file, call your insurer and ask. Many companies offer a quick phone assessment before you commit. You can also check if car insurance rates going up after a glass claim is a concern for your specific policy by reviewing your terms or speaking with an agent.
Also, keep in mind that in some states, you can claim car insurance on taxes under certain circumstances, particularly if the damage is related to a federally declared disaster. This is a niche situation, but it is worth knowing.
Comparison: Windshield Damage Coverage by Insurance Type
| Coverage Type | Covers Windshield Damage? | Typical Cost to You | Best For |
|---|---|---|---|
| Comprehensive | Yes — most damage types | Deductible (or $0 with glass add-on) | Rocks, hail, vandalism, weather |
| Collision | Sometimes — accident-related only | Deductible applies | Cracks from crashes or rollovers |
| Liability | No — covers others’ damage only | You pay full cost | N/A for your own glass |
| Glass Repair Add-On | Yes — zero deductible | $0 | Drivers who want no out-of-pocket cost |
| No Coverage | No | Full replacement cost | Drivers who pay cash for repairs |
What to Look for in a Windshield Repair Shop
Not all repair shops are created equal. When choosing where to get your windshield fixed, look for these qualities:
- Insurance certification: The shop should be certified by your insurance company and able to bill them directly.
- OEM or OEM-equivalent glass: Ask whether they use original manufacturer glass or high-quality aftermarket alternatives.
- Lifetime warranty: A reputable shop stands behind its work with a lifetime warranty on both materials and labor.
- Mobile service: Many shops now offer mobile windshield replacement. They come to you, which saves time and hassle.
- Clear pricing: The shop should explain all costs upfront, including any deductible and what your insurance covers.
Taking the time to choose a quality shop ensures your auto glass repair is done right the first time. A poorly installed windshield can leak, rattle, and even pop out in a crash. Do not settle for the cheapest option — prioritize safety and quality.
Key Takeaways
- Comprehensive coverage is essential: It is the primary insurance type that covers most forms of windshield damage.
- Repair before it becomes a replacement: Small chips are cheaper and faster to fix. Address them early to avoid a full windshield replacement.
- Ask about zero-deductible glass options: This add-on eliminates your out-of-pocket cost for glass claims entirely.
- Document everything: Photos, dates, and details make your insurance claim process smoother and faster.
- Filing a glass claim rarely raises rates: A single comprehensive glass claim is treated differently from accident claims by most insurers.
- Prevention saves money: Safe driving habits and proper windshield care reduce the chance of damage in the first place.
- Know your policy inside and out: Understanding your insurance coverage limits and exclusions prevents surprises when you need to file.
Final Thoughts
So, does car insurance cover windshield damage? In most cases, the answer is a clear yes — as long as you carry comprehensive coverage. Whether it is a tiny rock chip or a long crack from a storm, your policy likely has you covered.
The key is understanding your specific policy details. Know your deductible, check whether your insurer offers zero-deductible glass options, and understand the claims process before you need it. A few minutes of preparation now can save you hundreds of dollars and a lot of stress later.
Take care of your windshield today. Fix small chips before they spread. Park in covered areas when you can. And keep your auto insurance policy updated so you are always protected.
Your windshield is your window to the road. Treat it well, and it will keep you safe for miles to come.
Frequently Asked Questions
Does full coverage car insurance cover windshield damage?
Full coverage typically includes both liability and comprehensive coverage. Since comprehensive covers non-accident damage, yes, full coverage generally includes windshield damage from rocks, hail, vandalism, and weather events. However, if the damage comes from a collision, collision coverage applies instead.
Will my insurance pay for a cracked windshield if I was at fault?
If the crack happened during an accident where you were at fault, collision coverage would apply — not comprehensive. If the crack was caused by something unrelated to a crash (like a rock or hail), comprehensive coverage pays regardless of fault. Always check your specific policy for details on your insurance coverage limits.
How much does a windshield replacement cost with insurance?
With comprehensive coverage, you typically only pay your deductible. If you have a zero-deductible glass add-on, you pay nothing. Without insurance, a standard replacement costs between $150 and $800 depending on your vehicle and the type of glass used. You can also claim car insurance on taxes in rare disaster-related situations.
Can I choose any repair shop for my windshield claim?
Many insurers have preferred networks, but you often have the right to choose your own shop. Contact your provider before scheduling to confirm their requirements. Some companies allow you to pick any certified shop, while others require you to use an approved network. Getting multiple quotes is always a smart move.
How long does a windshield repair or replacement take?
A small chip repair takes about 30 minutes. A full windshield replacement typically takes one to two hours. Some shops offer mobile service that comes to your home or office. After a replacement, most insurers recommend waiting at least one hour before driving and 24 hours before washing your vehicle.
Does filing a windshield claim raise my insurance rates?
A single glass claim under comprehensive coverage rarely causes a rate increase. Insurers classify glass claims separately from accident claims. However, multiple claims in a short period or at-fault glass damage may lead to higher premiums. To understand how your specific policy is affected, you can review your terms or ask your agent about car insurance rates going up after a glass claim. Also, do you pay car insurance monthly or annually can factor into how any rate change affects your budget.
Frequently Asked Questions
What is Does Car Insurance Cover Windshield Damage?
Does Car Insurance Cover Windshield Damage is an important topic with many practical applications.