Does Car Insurance Cover Battery Replacement Costs
Car insurance may or may not cover battery replacement costs depending on your policy type, the cause of damage, and your specific coverage limits. Comprehensive coverage often pays for battery replacement when damage comes from events like accidents, vandalism, or weather. However, standard policies typically exclude wear-and-tear issues, including a battery that simply dies from old age. Understanding your auto insurance policy is the first step to knowing what is covered and what you will pay out of pocket.
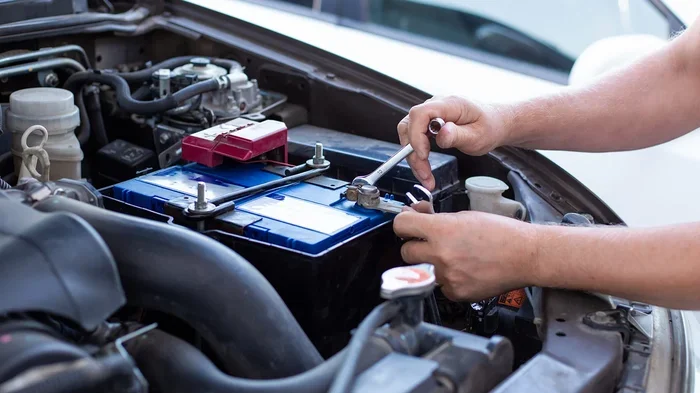
You turn the key, and nothing happens. No crank. No roar of the engine. Just silence. Your car battery is dead, and now you are staring at a repair bill that could cost anywhere from 50 to 200 dollars or more. The first question that pops into your mind is simple: does car insurance cover battery replacement? The answer is not a simple yes or no. It depends on several factors, including your type of coverage, the reason the battery failed, and the terms of your specific policy.
This guide breaks down everything you need to know about car insurance and battery replacement. We will walk through the different types of coverage, explain when insurance steps in and when it does not, and give you practical tips for getting the best outcome. By the end, you will feel confident about navigating your insurance claim and making smart decisions for your vehicle.
Key Takeaways
- Comprehensive coverage: This type of policy usually covers battery replacement when damage results from covered events like collisions, vandalism, or severe weather.
- Basic liability policies: These rarely cover battery replacement since they focus on damage you cause to others, not your own vehicle.
- Wear and tear exclusion: Most insurance companies exclude battery failure caused by normal aging or gradual degradation.
- Roadside assistance add-ons: Some policies include towing and jump-start services but may not pay for a full battery swap.
- Manufacturer warranty: A new car battery often falls under the manufacturer’s warranty, which may be a better first option than filing an insurance claim.
- Deductibles matter: Even when coverage applies, you must pay your deductible before the insurance company pays the rest.
- Document everything: Taking photos, getting repair estimates, and keeping receipts strengthens your insurance claim significantly.
📑 Table of Contents
- Understanding Car Insurance and Battery Replacement
- Types of Car Insurance Coverage That May Apply
- When Does Insurance Cover Battery Replacement?
- When Does Insurance NOT Cover Battery Replacement?
- How to File an Insurance Claim for Battery Replacement
- How to Prevent Battery Failure and Save Money
- Common Mistakes Drivers Make with Battery Claims
- Expert Insights on Battery Coverage
- Key Takeaways
- Frequently Asked Questions
- Conclusion
Understanding Car Insurance and Battery Replacement
Most drivers assume their auto insurance covers everything that goes wrong with their car. That is a common misconception. Insurance is designed to protect you from sudden, unexpected events. A battery that dies from old age is not a sudden event. But a battery damaged in a car accident or by a falling tree branch might be a different story entirely.
To understand whether your policy helps with a dead or damaged battery, you need to know how insurance companies classify different types of damage. They generally separate issues into two buckets: sudden and accidental damage versus gradual wear and tear. This distinction drives almost every decision about coverage.
What Does Your Policy Actually Cover?
Your insurance policy is a contract. It spells out exactly what is covered and what is not. Most standard auto insurance packages include liability coverage, which pays for damage you cause to other people or their property. This type of coverage has nothing to do with your own car’s battery. If your battery dies, liability coverage will not help you at all.
Beyond liability, there are additional coverage options you can add to your policy. These include collision coverage, comprehensive coverage, and various add-ons like roadside assistance. Each of these plays a different role when it comes to battery replacement. Let us explore them one by one.
Types of Car Insurance Coverage That May Apply
Not all insurance coverage is the same. Different types of policies offer different levels of protection for your vehicle. Here is a closer look at the coverage types that might come into play when your battery needs replacing.
Comprehensive Coverage
Comprehensive coverage is the most likely type of insurance to pay for a battery replacement. This coverage protects your car from damage caused by events that are not collisions. Examples include theft, vandalism, fire, flooding, hail, falling objects, and animal damage.
If a severe storm causes a power surge that damages your car battery, comprehensive coverage may step in. If someone vandalizes your vehicle and damages the battery, this coverage type could help pay for the replacement. The key question is always whether the cause of the damage falls within the covered events listed in your policy.
Collision Coverage
Collision coverage pays for damage to your car resulting from an accident with another vehicle or object. If you get into a fender bender and the impact damages your battery, collision coverage may apply. This is especially true if the battery becomes loose, cracks, or suffers internal damage due to the collision force.
However, if the battery simply dies after the accident due to a disconnected cable or a minor electrical issue, the insurance company might view this differently. It is always best to report any damage, even if you are unsure whether it qualifies. Your insurance provider can assess the situation and make a determination.
Roadside Assistance and Add-On Coverage
Many insurance companies offer roadside assistance as an add-on to your policy. This service typically includes towing, jump-starts, lockout assistance, and flat tire changes. A jump-start can temporarily bring your car back to life if the battery is simply drained.
But here is the catch. Roadside assistance usually does not pay for a full battery replacement. It helps you get back on the road in an emergency. If the battery is truly dead and needs to be replaced, you will likely need to rely on your comprehensive or collision coverage, or pay for the replacement yourself.
Manufacturer Warranty and Extended Warranty
Before you even think about filing an insurance claim, check your manufacturer warranty. Most new cars come with a battery warranty that covers defects for a certain period, usually three to five years or up to a specific mileage limit. If your battery fails due to a manufacturing defect, the manufacturer will likely replace it at no cost to you.
An extended warranty or a service contract may also cover battery replacement. These are worth checking before you go the insurance route. Filing a claim can affect your insurance premium down the road, so using a warranty first is often the smarter financial move.
When Does Insurance Cover Battery Replacement?
There are specific situations where your car insurance policy will cover the cost of replacing a battery. Understanding these scenarios helps you know when to file a claim and when to explore other options.
Accident-Related Battery Damage
If you are involved in a car accident and the battery gets damaged as a direct result, your collision or comprehensive coverage may pay for the replacement. This applies when the battery is physically damaged, cracked, or dislodged during the impact. Insurance adjusters will evaluate the damage and determine whether the battery replacement is a covered repair.
For example, imagine you rear-end another car at a stoplight. The impact shifts your engine components, and the battery terminal gets damaged. In this case, the battery replacement would likely be covered under your collision coverage, minus your deductible.
Weather and Natural Disaster Damage
Severe weather events can damage your car battery in ways that insurance may cover. A lightning strike during a thunderstorm can fry your electrical system, including the battery. Flooding can cause corrosion and short circuits that ruin a battery. Hail can crack the battery casing and cause internal damage.
These scenarios fall under comprehensive coverage in most policies. If you live in an area prone to storms, hurricanes, or flooding, having comprehensive coverage gives you valuable protection for these unexpected events.
Vandalism and Theft
If someone deliberately damages your car battery, comprehensive coverage typically applies. This includes situations where a thief steals the battery or vandals tamper with it. The key here is that the damage is sudden and intentional, not a result of normal use or aging.
Always report vandalism to the police and get a police report number. Your insurance company will almost always ask for this documentation before processing your claim. It strengthens your case and speeds up the approval process.
When Does Insurance NOT Cover Battery Replacement?
There are just as many situations where insurance will not cover a battery replacement. Knowing these helps you avoid filing a claim that will be denied and potentially waste your time.
Wear and Tear Exclusion
Almost every insurance policy includes a wear and tear exclusion. This means that damage caused by normal use, aging, or gradual deterioration is not covered. A car battery that simply dies after three or four years of regular use falls squarely into this category.
Insurance companies view battery aging as a normal maintenance issue, not an insured event. Replacing a worn-out battery is considered part of routine car maintenance, similar to oil changes or tire rotations. You should expect to pay for these replacements yourself.
Gradual Battery Failure
Even if your battery does not simply die of old age, gradual failure is usually not covered. For instance, if your battery has been slowly losing capacity over months and eventually fails to start your car, this is seen as a gradual process. Insurance companies distinguish between sudden, accidental damage and slow, progressive failure.
If you notice your battery struggling to start your car for weeks before it finally dies completely, that is gradual failure. A claim for this type of issue will almost certainly be denied.
Neglect and Maintenance Issues
Batteries need regular maintenance. Corroded terminals, loose connections, and dirty battery cables can all contribute to battery failure. If your battery dies because you neglected basic maintenance, your insurance company will not cover the replacement cost.
This includes situations where you leave your lights on repeatedly or fail to drive your car regularly enough to keep the battery charged. Insurance policies expect vehicle owners to maintain their cars properly. Neglect is not a covered event.
Pre-Existing Damage
If your battery was already damaged or weak before an accident or event, the insurance company may deny the claim. They will investigate whether the battery failure was caused by the covered event or was simply a pre-existing condition that the event exposed.
This is why it is important to report battery damage promptly after an incident. Delaying the report gives the insurance company grounds to argue that the damage was not caused by the covered event.
How to File an Insurance Claim for Battery Replacement
If you believe your situation qualifies for coverage, filing a claim is the next step. Here is a practical guide to help you navigate the process smoothly.
Step 1: Document the Damage
Before you do anything else, take clear photos of the damaged battery and the surrounding area. Capture any visible damage, corrosion, or breakage. If the battery failure resulted from an accident, take photos of the entire scene, including vehicle damage and any relevant road conditions.
Write down a detailed description of what happened. Include the date, time, location, and circumstances. The more documentation you have, the stronger your claim will be.
Step 2: Contact Your Insurance Company
Call your insurance provider as soon as possible after the incident. Report the damage and provide all the documentation you collected. Be honest and accurate in your description. Do not exaggerate or speculate about the cause of the damage.
Your insurance company will assign a claim number and may ask you to visit an approved repair shop or provide an estimate from a certified mechanic. Follow their instructions carefully to avoid delays.
Step 3: Get an Estimate
Ask your mechanic or repair shop for a written estimate for the battery replacement. The estimate should include the cost of the new battery, labor charges, and any related fees. Some insurance companies have preferred repair networks. Check if your provider has one and whether using it saves you money.
Keep in mind that you will need to pay your deductible before the insurance company covers the remaining cost. If the battery replacement cost is close to or lower than your deductible, it might not be worth filing a claim at all.
Step 4: Wait for the Claim Decision
After you submit your claim and documentation, the insurance company reviews everything. They may send an adjuster to inspect the damage in person. This process can take anywhere from a few days to a few weeks depending on the complexity of the claim.
If the claim is approved, the insurance company pays the repair cost minus your deductible. If it is denied, they will explain why. You have the right to appeal a denied claim or seek a second opinion.
Quick Tips for a Smooth Claim Process
- Always keep your policy documents and claim number handy.
- Respond to your insurance company’s requests promptly.
- Do not repair the damage before the adjuster inspects it.
- Keep all receipts related to the incident, including towing costs.
- Ask questions if you do not understand any part of the process.
How to Prevent Battery Failure and Save Money
Prevention is always better than dealing with a claim. Regular battery maintenance can extend its life and save you from unexpected replacement costs. Here are some practical steps you can take.
Regular Battery Inspections
Have your battery inspected at least twice a year, especially before winter and summer. Extreme temperatures are the biggest enemies of car batteries. Cold weather reduces battery capacity, while hot weather accelerates fluid evaporation and internal corrosion.
During an inspection, a mechanic checks the battery voltage, tests the charging system, and looks for signs of corrosion or damage. Catching problems early can prevent a sudden failure that leaves you stranded.
Keep Your Battery Clean
Corrosion buildup on battery terminals is a common cause of starting problems. You can clean the terminals yourself using a baking soda and water solution and a wire brush. Wipe the terminals dry after cleaning and apply a thin layer of petroleum jelly to prevent future corrosion.
This simple maintenance task takes just a few minutes and can add months or even years to your battery’s life.
Avoid Short Trips When Possible
Short trips do not give your battery enough time to fully recharge. Over time, this can weaken the battery and shorten its lifespan. If you frequently take short drives, consider using a battery maintainer or trickle charger to keep the battery topped up.
Turn Off Accessories When the Engine Is Off
Leaving your headlights, interior lights, or radio on when the engine is not running drains the battery quickly. Make it a habit to check that all accessories are off before you turn off the engine and walk away from your car.
Common Mistakes Drivers Make with Battery Claims
Avoiding common mistakes can save you time, money, and frustration. Here are some pitfalls to watch out for.
Filing a Claim for Wear and Tear
Many drivers assume that any car problem is covered by insurance. Filing a claim for a battery that died from old age will result in a denial. Not only does this waste your time, but it can also create a claim record that may affect your future premiums.
Not Checking the Warranty First
Before filing an insurance claim, always check your manufacturer warranty and any extended warranty you may have. If the battery is still under warranty, using that coverage is almost always the better option. It avoids the claim process and protects your insurance record.
Ignoring the Deductible
Some drivers forget to factor in their deductible when deciding whether to file a claim. If the battery replacement costs 120 dollars and your deductible is 500 dollars, filing a claim makes no financial sense. You would pay the full cost out of pocket either way.
Delaying the Claim Report
Insurance companies expect prompt reporting. Delaying the claim by days or weeks can raise questions about the cause of the damage and may lead to a denial. Report any incident as soon as you reasonably can.
Expert Insights on Battery Coverage
Insurance professionals often emphasize one key point: read your policy carefully. Every policy is different, and the fine print determines exactly what is covered and what is not. Do not assume that because your friend’s claim was approved, yours will be too.
Experts also recommend shopping around for the right coverage. If you live in an area with extreme weather or high crime rates, comprehensive coverage is a smart investment. It protects you from a wide range of non-collision events, including battery damage from storms, flooding, and vandalism.
Another expert tip is to understand the difference between a claim and a complaint. A claim is a formal request for payment under your policy. A complaint is a general expression of dissatisfaction. Knowing this difference helps you communicate effectively with your insurance company and get better results.
Key Takeaways
- Comprehensive coverage: This type of policy usually covers battery replacement when damage results from covered events like collisions, vandalism, or severe weather.
- Basic liability policies: These rarely cover battery replacement since they focus on damage you cause to others, not your own vehicle.
- Wear and tear exclusion: Most insurance companies exclude battery failure caused by normal aging or gradual degradation.
- Roadside assistance add-ons: Some policies include towing and jump-start services but may not pay for a full battery swap.
- Manufacturer warranty: A new car battery often falls under the manufacturer’s warranty, which may be a better first option than filing an insurance claim.
- Deductibles matter: Even when coverage applies, you must pay your deductible before the insurance company pays the rest.
- Document everything: Taking photos, getting repair estimates, and keeping receipts strengthens your insurance claim significantly.
Frequently Asked Questions
Does full coverage car insurance cover battery replacement?
Full coverage typically includes both collision and comprehensive coverage. If your battery is damaged in a covered event like an accident, vandalism, or severe weather, full coverage may pay for the replacement. However, full coverage does not pay for batteries that fail due to normal wear and tear or old age.
How much does a car battery replacement cost without insurance?
The cost of a car battery replacement typically ranges from 50 to 200 dollars for the battery itself, plus 20 to 100 dollars for labor. Premium or luxury vehicles may cost more. The total expense depends on the battery type, your vehicle model, and where you live.
Will filing a battery replacement claim raise my insurance premium?
It depends. If the claim is covered under comprehensive or collision coverage, it may go on your claims history. Multiple claims within a short period can lead to higher premiums. However, a single comprehensive claim for an event like vandalism or weather damage usually has a smaller impact than a collision claim.
Can I get my battery replaced for free through insurance?
You can get a free battery replacement only if your policy covers the specific cause of damage and your deductible is zero. Some policies offer zero-deductible options for comprehensive coverage, but these are rare. Most drivers will need to pay at least a portion of the replacement cost.
Does roadside assistance cover battery replacement?
Roadside assistance typically covers jump-starts and towing but does not pay for a full battery replacement. It is designed to get you back on the road quickly in an emergency, not to cover replacement parts. Check your specific roadside assistance plan for details on what is included.
How long does a car insurance claim for battery replacement take to process?
The processing time varies depending on the insurance company and the complexity of the claim. Simple claims with clear documentation may be approved within a few days. More complex claims that require an adjuster inspection or additional evidence can take one to three weeks. Prompt reporting and complete documentation help speed up the process.
Conclusion
The question of whether car insurance covers battery replacement does not have a one-size-fits-all answer. Your coverage type, the cause of the battery failure, and the terms of your specific policy all play a role. Comprehensive coverage offers the best protection for non-accident battery damage, while collision coverage applies when an accident is the cause. Basic liability policies and wear-and-tear exclusions typically leave battery replacements uncovered.
The smartest approach is to understand your policy before you need it. Read your coverage details, know your deductible, and keep your manufacturer warranty information in a safe place. When a battery does fail, document everything, report the claim promptly, and explore all your options including warranties and roadside assistance.
Taking a few minutes to review your auto insurance policy today can save you significant time and money tomorrow. Stay proactive, stay informed, and make sure your coverage matches your real-world needs. Your car battery may be small, but the financial impact of replacing it can be significant. Make sure you are prepared.