How Much Is a Monthly Car Payment and What Affects It
A monthly car payment depends on several key factors, including the loan amount, interest rate, and loan term. On average, most car buyers pay between $400 and $700 per month, but your numbers could be higher or lower based on your credit score, down payment, and whether you buy new or used. Understanding what drives your payment helps you make smarter financing decisions.
Key Takeaways
- Loan amount and term: The size of your loan and how long you pay it back directly impact your monthly car payment.
- Interest rates matter: Your credit score determines the APR, which can add thousands to your total cost.
- Down payments reduce monthly costs: Putting more money down lowers the loan principal and shrinks each payment.
- New vs. used affects price: Used car loans often have lower monthly car payments than new car loans.
- Lease vs. buy: Lease payments are typically lower but come with mileage limits and no ownership.
- Budget wisely: Experts recommend keeping your auto payment under 10-15% of your monthly income.
📑 Table of Contents
How Much Is a Monthly Car Payment and What Affects It
If you have ever wondered, “how much is a monthly car payment,” you are not alone. Thousands of shoppers search for this exact question every month. Whether you are buying your first vehicle or upgrading your current ride, understanding your financing options is essential. The truth is, there is no single answer. Your monthly car payment depends on several factors that are unique to your situation.
On average, Americans pay somewhere between $400 and $700 per month for a car loan. But that range is just a starting point. Your actual number could fall well below or above that depending on your credit score, the loan term, the down payment, and whether you are buying a new or used vehicle. This guide breaks down everything you need to know about auto loan payments, what drives them up or down, and how to find a payment that fits your budget.
We will walk you through the math in plain English. No jargon. No confusing formulas. Just clear, practical advice that helps you walk into a dealership or bank with confidence. Let us dive in.
What Is a Monthly Car Payment?
A monthly car payment is the amount you pay each month to finance a vehicle. This payment covers the loan principal plus interest and any applicable fees. When you finance a car, you are essentially borrowing money from a lender to cover the purchase price. You then repay that amount over a set period, usually between 36 and 84 months.
Every auto loan has a few core components. The loan principal is the amount you borrow. The interest rate, often called the APR, is what the lender charges you for the privilege of borrowing. The loan term is how long you have to repay the full amount. Together, these three elements determine your monthly car payment. If you increase the principal or the interest rate, your payment goes up. If you extend the loan term, your payment goes down, but you pay more in interest over time.
Average Monthly Car Payment by Vehicle Type
The type of vehicle you choose plays a big role in your monthly car payment. New cars cost more than used cars, and luxury vehicles cost more than economy models. Here is a closer look at what different buyers typically pay.
New Car Payments
According to recent industry data, the average monthly car payment for a new car in the United States hovers around $700 to $750. New car prices have risen significantly in recent years, pushing payments higher. The average transaction price for a new vehicle now exceeds $48,000. That is a lot of money to finance. Add in a typical interest rate of around 7%, and you are looking at a substantial monthly obligation.
However, new cars come with advantages. They usually have lower interest rates because lenders view them as less risky. New vehicles also come with warranties that cover repairs for the first few years. This means fewer unexpected costs during the early years of ownership.
Used Car Payments
Used car payments are typically lower than new car payments. The average monthly car payment for a used vehicle ranges from about $400 to $550. Used cars depreciate faster in the first few years, so their resale value is lower. This means lenders finance less money, which reduces your monthly car payment.
One thing to watch out for is higher interest rates on used car loans. Because older vehicles carry more risk for lenders, the APR tends to be higher. A used car loan might carry an interest rate of 8% or more, depending on your credit profile. This can offset some of the savings from a lower purchase price.
Factors That Affect Your Monthly Car Payment
Several factors influence how much your monthly car payment will be. Understanding each one helps you take control of your financing. Let us break them down.
Credit Score
Your credit score is one of the biggest factors in determining your auto loan interest rate. Lenders use your credit score to assess how risky it is to loan you money. A higher credit score means a lower interest rate, which means a lower monthly car payment. A lower credit score means a higher interest rate, which increases your payment.
Here is how credit scores typically affect auto loan rates. Borrowers with excellent credit (720 and above) often qualify for rates around 5% to 6%. Those with good credit (680 to 719) might see rates between 6% and 8%. Fair credit (620 to 679) can push rates to 9% or higher. And borrowers with poor credit (below 620) may face rates of 12% or more. Even a small difference in interest rate can add up to hundreds or thousands of dollars over the life of the loan.
Down Payment Amount
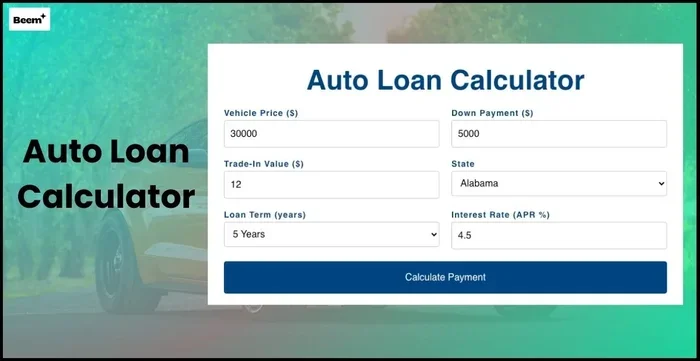
The down payment is the cash you pay upfront when purchasing a vehicle. A larger down payment reduces the loan principal, which directly lowers your monthly car payment. For example, if you buy a car for $35,000 and put down $5,000, you only need to finance $30,000. But if you put down $10,000, you only finance $25,000. That $5,000 difference can save you $50 or more per month, depending on the interest rate and loan term.
Many financial experts recommend putting down at least 20% of the vehicle price. This helps you avoid being underwater on the loan, which means owing more than the car is worth. Being underwater can make it very difficult to sell or trade in the vehicle later.
Loan Term Length
The loan term is the length of time you have to repay the auto loan. Common terms include 36 months, 48 months, 60 months, 72 months, and 84 months. A shorter loan term means higher monthly payments, but you pay less in total interest. A longer loan term means lower monthly car payments, but you end up paying more in interest over the life of the loan.
For example, a $25,000 loan at 7% interest over 36 months might result in a monthly payment of about $775. The same loan over 72 months might drop the payment to around $405. But the total interest paid over 72 months would be much higher than over 36 months. It is a trade-off between monthly affordability and total cost.
Trade-In Value
If you have a vehicle to trade in, its value reduces the total amount you need to finance. A strong trade-in can significantly lower your monthly car payment. The trade-in value depends on the vehicle’s age, mileage, condition, and market demand. You can check your trade-in value using online tools or by visiting dealerships for estimates.
Be careful with negative equity. If you owe more on your current car than it is worth, that negative equity can roll into your new loan, increasing the principal and your monthly payment. This is sometimes called rolling negative equity into a new loan, and it can quickly lead to financial trouble.
Monthly Car Payment: New vs. Used vs. Lease
Not all auto financing options are the same. Let us compare the three most common paths: buying new, buying used, and leasing.
Buying a New Car
Buying a new car typically results in the highest monthly car payment. New vehicles come with higher sticker prices, and the loan amounts are larger. However, new car loans often have the lowest interest rates. The average new car loan lasts about 69 months to 72 months these days, which keeps monthly payments manageable despite the higher price tag.
New cars also come with the latest safety features, technology, and manufacturer warranties. These benefits can save you money on repairs and maintenance during the first several years of ownership.
Buying a Used Car
Used car financing usually offers lower monthly car payments. The purchase price is lower, which means a smaller loan amount. However, used car loans may have slightly higher interest rates. The average used car loan term is around 65 months to 72 months.
Buying used can be a smart financial move. The steepest depreciation happens in the first three years, so a 3-to-5-year-old vehicle has already lost a significant portion of its value. You get the benefit of the vehicle while avoiding the worst of the depreciation hit.
Leasing a Vehicle
Leasing is different from buying. When you lease, you are essentially renting the vehicle for a set period, usually 24 to 36 months. Lease payments are typically lower than loan payments because you are only paying for the vehicle’s depreciation during the lease term, not the full purchase price.
The average lease payment is around $500 to $600 per month. However, leases come with restrictions. Most leases limit you to a certain number of miles per year, usually 10,000 to 15,000 miles. Exceeding that limit can result in extra charges at the end of the lease. You also do not own the vehicle at the end of the lease term.
| Option | Average Monthly Payment | Ownership | Typical Term | Key Benefit |
|---|---|---|---|---|
| New Car Loan | $700 – $750 | Yes | 60 – 72 months | Latest features and warranty |
| Used Car Loan | $400 – $550 | Yes | 60 – 72 months | Lower cost and slower depreciation |
| Lease | $450 – $600 | No | 24 – 36 months | Lowest monthly payment |
How to Lower Your Monthly Car Payment
If your current or projected monthly car payment feels too high, there are several strategies you can use to bring it down. Here are some practical tips that really work.
Increase Your Down Payment
The simplest way to reduce your monthly car payment is to put more money down. Every extra dollar you add to the down payment reduces the loan principal and lowers the monthly payment. If you can save an additional $2,000 or $3,000 before you buy, it can make a noticeable difference in your budget.
Improve Your Credit Score Before Applying
Even a small improvement in your credit score can unlock a lower interest rate. Before you apply for an auto loan, check your credit report for errors. Pay down any outstanding debts. Avoid opening new credit accounts. These steps can boost your score enough to qualify for a better rate, which directly lowers your monthly car payment.
Shop Around for the Best Loan
Do not accept the first financing offer you receive. Dealerships often mark up interest rates for profit. Instead, get preapproved from a bank or credit union before you visit the dealership. Having a preapproval gives you a baseline rate to compare against. You can then negotiate from a position of strength.
Choose a Shorter Loan Term
While a longer loan term lowers your monthly payment, it increases the total interest you pay. If you can afford a slightly higher monthly payment, choose a shorter term. You will save money overall and own the vehicle sooner. A 48-month or 60-month loan is often a sweet spot for balancing affordability and total cost.
Consider a Less Expensive Vehicle
Sometimes the best way to lower your payment is to adjust your expectations. A slightly less expensive vehicle can reduce the loan amount significantly. You do not need the top trim level or every available feature. Focus on what you actually need and let go of the extras.
Common Mistakes That Increase Your Monthly Car Payment
Many buyers unknowingly make mistakes that drive up their monthly car payment. Being aware of these pitfalls helps you avoid them.
Ignoring the Total Cost of Ownership
The monthly car payment is not the only cost of owning a vehicle. You also need to pay for insurance, fuel, maintenance, and registration. Some vehicles cost much more to insure than others. Before you commit to a loan, calculate the full monthly cost of ownership, not just the payment.
Rolling Negative Equity Into a New Loan
If your current car is worth less than what you owe, rolling that negative equity into a new loan increases the principal. This raises your monthly car payment and puts you deeper underwater. It is almost always better to wait until you have positive equity before trading in or selling your vehicle.
Choosing the Longest Loan Term Available
Extended loan terms like 84 months make monthly payments seem affordable, but they are deceptive. You pay more in interest over the life of the loan, and the vehicle depreciates faster than the loan balance shrinks. This creates a dangerous gap between what you owe and what the car is worth.
Focusing Only on the Monthly Payment
Dealers sometimes focus on the monthly payment to close a deal, rather than the total cost. They might extend the loan term or add extras to keep the payment low while increasing the total amount you pay. Always negotiate based on the total vehicle price, not the monthly payment.
Expert Insights on Auto Loan Payments
Financial advisors and auto industry experts agree on a few key principles when it comes to auto financing. First, always get preapproved before stepping onto a lot. This gives you a clear picture of what you can afford and protects you from high-pressure sales tactics.
Second, keep your total debt-to-income ratio in mind. Lenders generally want your total monthly debt payments, including the auto loan, to be no more than 36% to 43% of your gross monthly income. Staying within this range keeps your finances healthy and gives you breathing room for savings and emergencies.
Third, read the full loan contract before signing. Look for hidden fees, prepayment penalties, and add-ons like extended warranties or gap insurance. Some of these products are valuable, but others are pure profit for the dealer. Know exactly what you are agreeing to.
Finally, remember that a car is a depreciating asset. It loses value the moment you drive it off the lot. Do not borrow more than you can comfortably afford. The goal is to get reliable transportation without sacrificing your financial health.
Key Takeaways
- Your monthly car payment is shaped by the loan amount, interest rate, and loan term. Understanding these three factors gives you control over your financing.
- Credit score matters a lot. A higher score leads to lower rates and lower payments. Take time to improve your credit before applying.
- A larger down payment reduces your monthly car payment and protects you from negative equity. Aim for at least 10% to 20% down.
- Shorter loan terms save you money in the long run. They may have higher monthly payments, but the total interest cost is much lower.
- Used cars generally offer lower monthly car payments than new cars. They also depreciate more slowly, which protects your investment.
- Avoid common financing mistakes. Do not roll negative equity into a new loan, and do not focus solely on the monthly payment during negotiations.
Frequently Asked Questions
What is the average monthly car payment for a new car?
The average monthly car payment for a new car in the United States is around $700 to $750. This figure varies based on the vehicle price, interest rate, and loan term. New car prices have been rising, which pushes the average payment higher each year.
How does my credit score affect my monthly car payment?
Your credit score directly affects the interest rate you receive on an auto loan. A higher credit score qualifies you for a lower APR, which reduces your monthly car payment. A lower credit score results in a higher interest rate and a higher monthly payment. Improving your credit score even a few points can save you significant money over the life of the loan.
Is it better to have a shorter or longer car loan term?
A shorter loan term means higher monthly payments but less total interest paid. A longer loan term means lower monthly car payments but more interest over time. Most financial experts recommend a 48-month to 60-month loan as a good balance between affordability and cost. Avoid extending the term just to lower the monthly payment if you can afford a higher one.
How much should I put down on a car?
Financial experts recommend putting down at least 10% to 20% of the vehicle price. A larger down payment reduces the loan principal, lowers your monthly car payment, and helps you avoid negative equity. If you cannot afford a 20% down payment, put down as much as you comfortably can.
Can I lower my monthly car payment after getting the loan?
Yes, there are a few ways to lower your monthly car payment after closing the loan. You can refinance the loan at a lower interest rate if your credit score has improved. You can also make extra principal payments to reduce the balance faster. However, some loans come with prepayment penalties, so check your contract before making extra payments.
What is a good monthly car payment for my budget?
A good rule of thumb is to keep your monthly car payment under 10% to 15% of your take-home pay. This leaves enough room in your budget for other expenses, savings, and emergencies. When calculating affordability, also factor in insurance, fuel, and maintenance costs. The total cost of ownership matters just as much as the payment itself.
Conclusion
Understanding how much a monthly car payment costs and what affects it puts you in a much stronger position when buying a vehicle. The monthly car payment is shaped by your loan amount, interest rate, credit score, down payment, and loan term. Each of these factors is something you can influence with preparation and smart decision-making.
Take the time to get preapproved, compare offers, and negotiate based on the total price, not the monthly number. Avoid common traps like rolling negative equity into a new loan or choosing an excessively long loan term just to lower the payment. These shortcuts may feel appealing in the moment but can cost you thousands of dollars over time.
Whether you are buying a new car, a used car, or exploring a lease, the principles remain the same. Know your budget, understand the terms, and make a decision that supports your long-term financial health. A well-planned auto loan gives you reliable transportation without the financial stress. Use the tips in this guide to find a monthly car payment that works for you and drives you toward a smarter financial future.